For Sellers • Home Prices • June 26, 2026

Your House Didn’t Sell. Here’s How To Turn It Around.

When your house doesn’t sell, it’s not just disappointing. It messes with your timing. Your plans. Your confidence. You start second-guessing everything, including the decision to move in the first place. And that raises 2 big questions: 

Do you try again?

Is that even worth it?

Here’s the secret to getting a better outcome the second time around.

Different Agent. Different Results.

Most sellers who re-list and ultimately sell don’t wait for market to magically change. They change their approach. And there’s data to back that up.

Research from REDX shows homeowners who put their house back on the market with a different agent are more likely to sell than homeowners who re-used the same agent. Not to mention, they see their homes sell faster (see graph below):
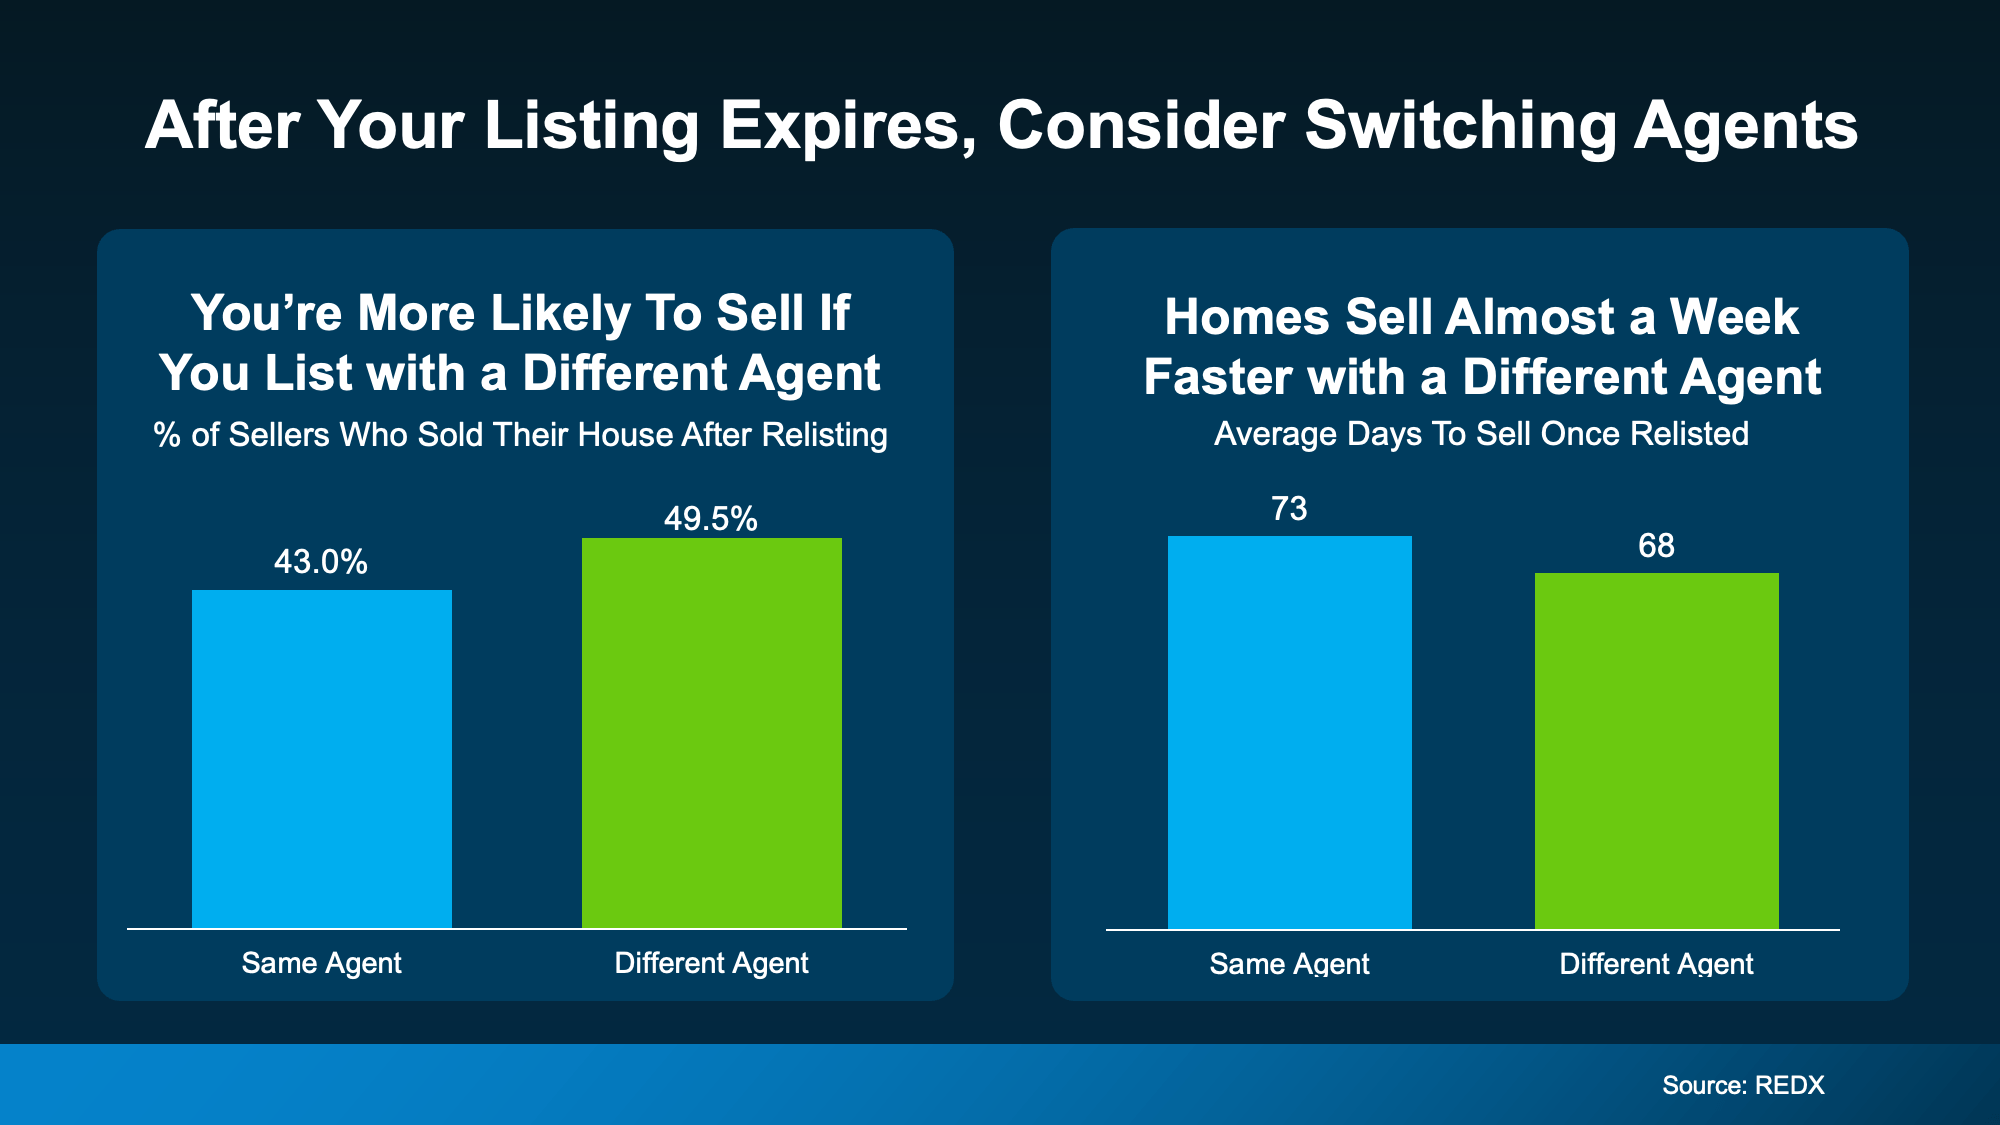
a screenshot of a graph

That’s the power of a fresh set of eyes. Because in a moment like this, the worst thing you can do is rerun the same set of plays and expect a different outcome. A different agent can bring a new perspective on where things went off track – and a lot of the time, one of these things happened.

1. The Asking Price Didn’t Match Buyer Reality

There’s a saying that’s especially important in today’s market, and it’s: “if your price isn’t compelling, it’s not selling.” Maybe that’s what happened with your house.

With mortgage rates where they are and inflation driving up the cost of everyday purchases, buyers have less room to stretch. If they feel like your house is priced even a little high, it’s going to get skipped over. And if no one looks at it, it’s not going to sell.

The Fix: Price to draw buyers in, not push them away. Have an agent pull fresh data from recent sales so your asking price matches what buyers are actually paying right now.

2. The First Impression Didn’t Win the Click 

Most buyers decide whether they want to tour a home in seconds. If the photos look dark, or dated, they scroll right past. And while you may think: “If they just saw it in person, they’d get it,” you may not get that chance.

And honestly, even in person, small things can quietly kill momentum – worn down paint, outdated fixtures, clutter, or a yard that feels high-maintenance. Individually, they’re small. Stacked together, they create doubt.

The Fix: Walk the house like you’re a buyer, not the owner. Start with what’s easy and obvious – paint, lighting, curb appeal, decluttering. Then update the photos so they match the best version of your house.

3. The Marketing Was Too “Set It and Forget It”

Today, the number of homes for sale has grown in many areas. Buyers have more options, which means your house needs a plan to stand out. A generic description and a basic upload to the MLS can blend in fast.

The Fix: Find an agent who can build stronger exposure through digital marketing and social platforms, plus content that makes buyers stop – strong photos, a smart description, a video walk-through, and a plan for open houses and follow-up.

4. There Was No Clear Plan for Feedback

Sometimes the house gets showings, but no offers. If that was your experience, it actually tells you something important. Buyers liked it enough online to come see it. So, something else was holding them back.

Those buyers were sending a message. It just wasn’t translated into action.

The Fix: Make sure your agent has a clear plan for seeking out and acting on feedback quickly. That dialogue often points to the one change that would get a house sold.

5. The Deal Couldn’t Get Over the Finish Line 

Even when a house is priced well and marketed right, deals fall apart when there’s no plan for the human side of the transaction.

Buyers today are more likely to ask for repairs, credits, or help with closing costs than a few years ago. In this type of market, being unwilling to negotiate can cost you more than a reasonable concession ever would.

The Fix: Decide ahead of time what matters most to you and where you can be flexible. Keep the dialogue open and lean on your agent for advice.

Bottom Line

If your house didn’t sell the first time, you’re not stuck. You just need a different strategy, and maybe a different partner.

When you’re ready for a fresh set of eyes on what happened and what to change first, let’s connect.
For Buyers • For Sellers • Forecasts • Home Prices • Mortgage Rates • May 28, 2026

The Truth About Affordability Today

Let’s be real with each other for a second about affordability. Because you deserve someone who will be honest and transparent about what’s going on, especially if you’ve got a move on your mind.

Here’s the full picture of what’s happening and why. The good – and the bad. So, you know what it truly means for your move. Because while rates are certainly a big part of affordability, they’re not the only factor at play.

Mortgage Rates Have Been Rising

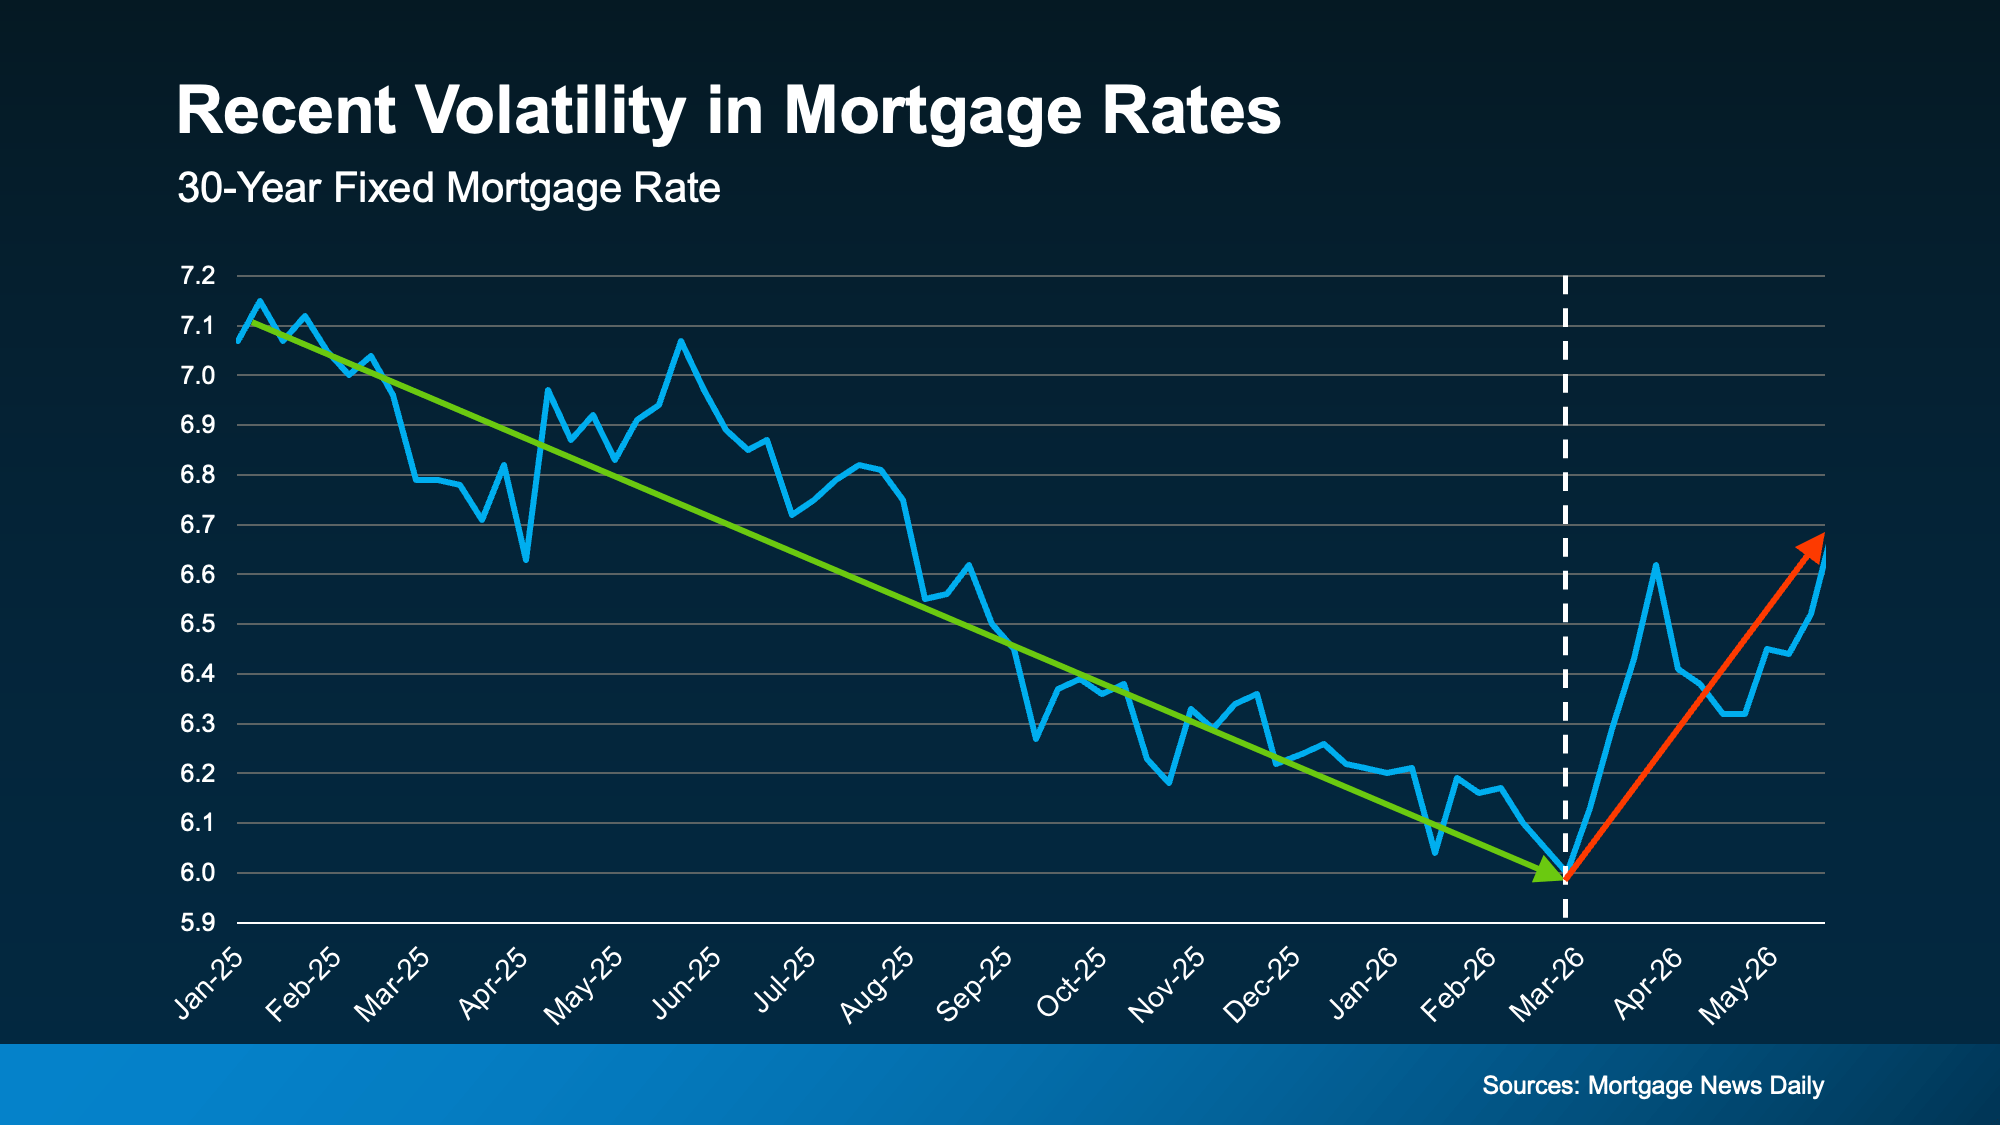
After a year or more of rates trending down, they’ve started to climb again. And, if you’re looking to buy, that’s not what you want to see. But it has happened. And here’s why.

Uncertainty is the enemy of mortgage rates.

And with lingering global uncertainty, ongoing tensions in the Middle East, and inflation refusing to fully cool off, there’s a lot that’s having an effect on rates. Colin Robertson, Founder of The Truth About Mortgage, put it plainly:

“You can’t have $100 a barrel oil and not expect inflation to rise, which translates to higher bond yields and mortgage rates.”

Take a look at the graph below. It uses data from Mortgage News Daily to show just how much all of those factors have had an impact:

a graph with a line and a green arrowIt’s a pretty sharp contrast from where we’ve been, in a relatively short window. And it’s probably making you wonder: Should I just wait this out? Will rates fall when the uncertainty eases?
It’s possible. But it all depends on how the ongoing geopolitical conflict plays out and whether inflation continues to run hot afterwards – and for how long.

Rates probably aren’t heading down until both of those things improve. And even when that does happen, experts agree rates likely won’t be dramatically lower – maybe in the low to mid-6s. That’s the reality, and it’s worth knowing.

So, should you wait for lower rates? The general consensus is, if you can afford to buy and you find a home you like, it’s still worth it. Because no one knows for sure when rates will start to come back down – and how long do you really want to put your life on hold?

Wages Are Outpacing Home Prices

You’ve probably heard that inflation is making everything more expensive, and there’s no shortage of headlines about the cost-of-living outpacing paychecks. It’s a legitimate concern. And maybe you’re feeling the pinch yourself. But here’s what doesn’t make the headlines. It’s not all bad news.

Data from the Federal Reserve Bank of Atlanta and Redfin shows wages have actually been growing faster than home prices.

  • Recently, wages have been increasing at around 4% year-over-year.
  • And home price growth is closer to 2% year-over-year.

As a buyer, you want your income to rise faster than prices because that helps make your purchase more manageable financially, and it quietly chips away at the affordability challenge over time. That’s exactly what we’re seeing lately. And every little bit is going to help.

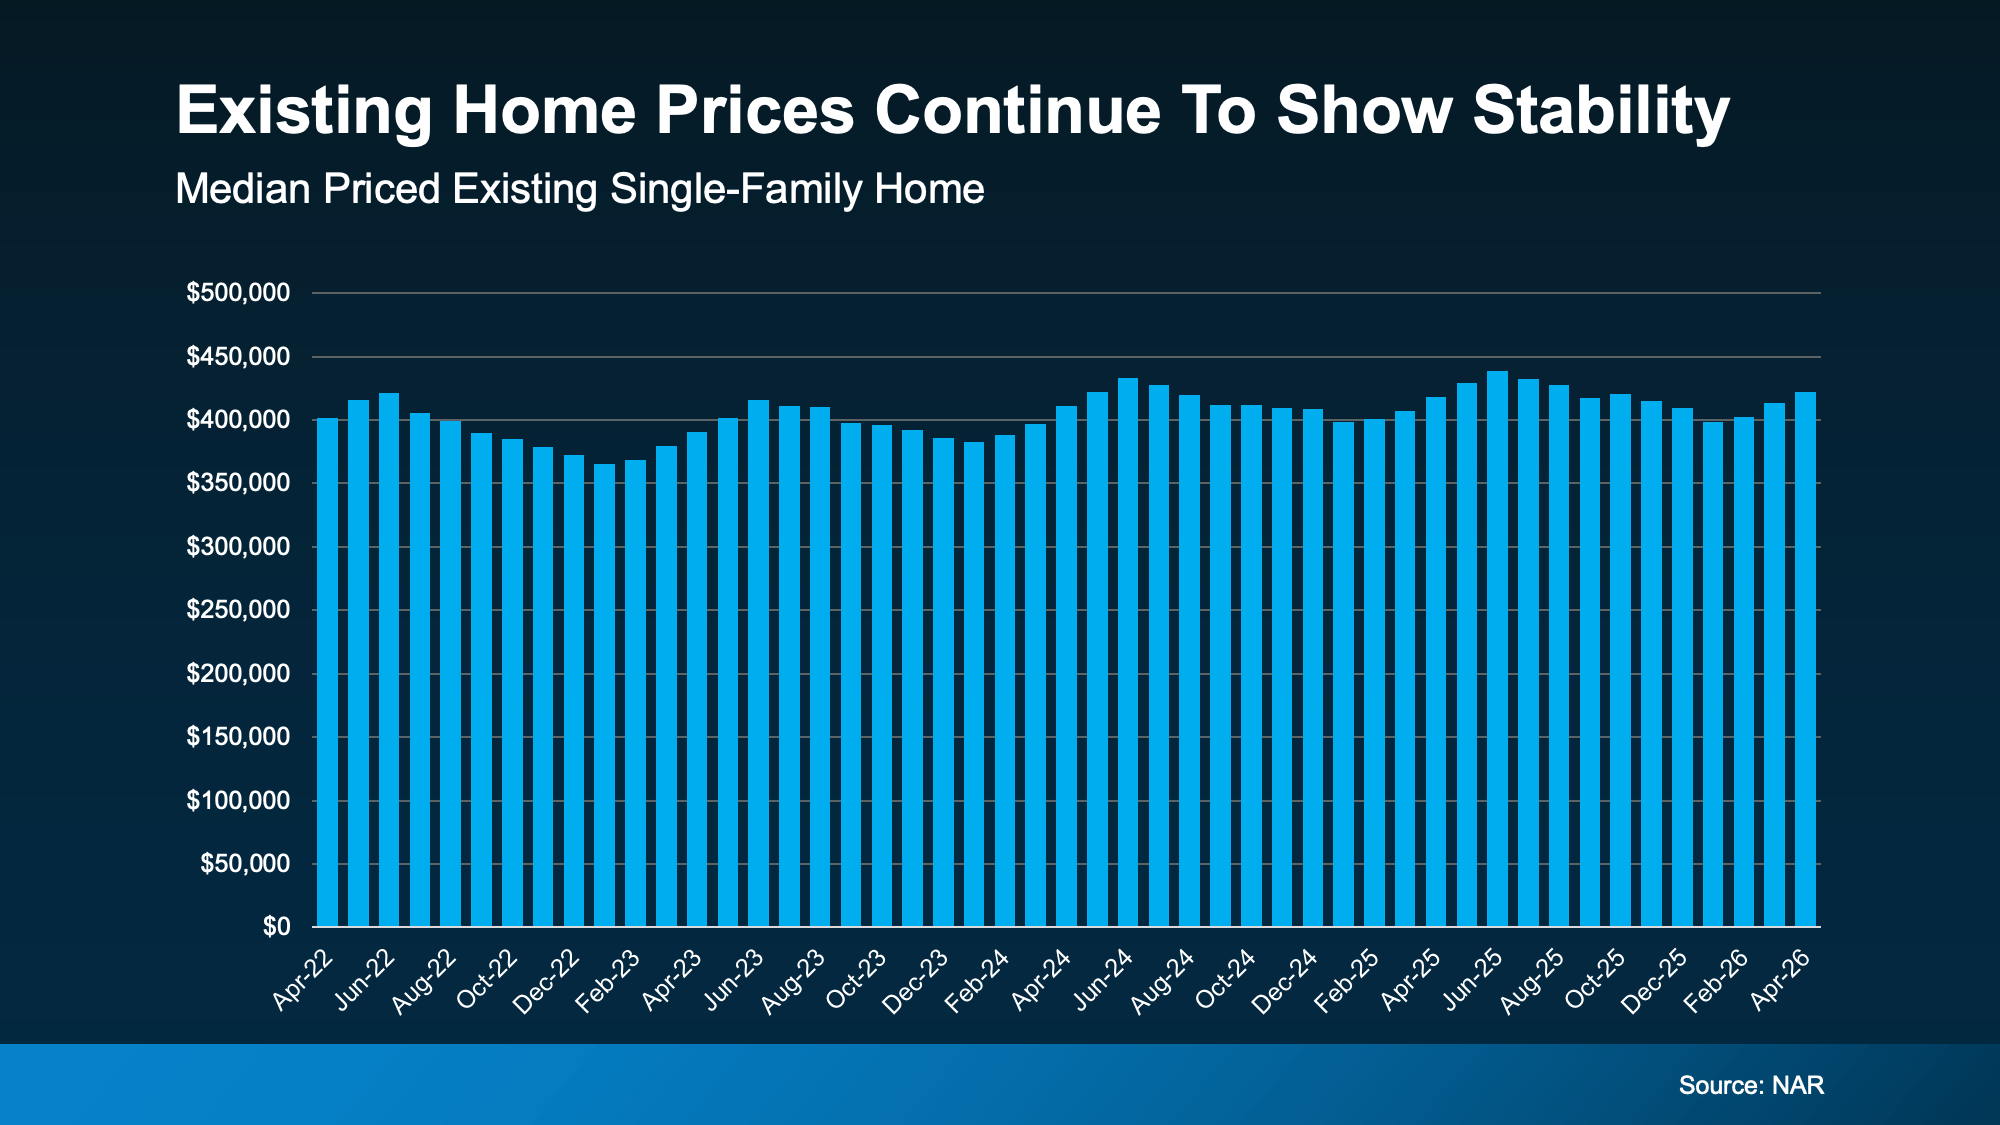
A big reason wages have been gaining ground on home prices? Home prices have actually stayed pretty steady.

Existing Home Prices Have Held Steady

Check out the graph below. It shows home price data from the National Association of Realtors (NAR) over the past 4 years. Notice anything? There’s been no dramatic runup, and no crash either. Just relative stability and slow growth:

a graph of blue lines

Part of what’s keeping prices this stable is that buyers finally have more choices. That means less competition, more negotiating power, and more time to find the home that actually fits your life, not just the one you had to grab before someone else did.

And that gives you a chance to hopefully find something that works for your budget, even with today’s rates. At the same time, you’re not losing ground pricewise while you take time to make a careful decision.

Bottom Line

Yes, rates have been volatile, and global instability is keeping them from settling down anytime soon. There’s no sugar coating that. But the full picture of affordability is more nuanced than the headlines suggest.

Want to run the real numbers for your situation? Let’s talk. Reach out and let’s set up a quick, no-pressure conversation.

For Buyers • Forecasts • Home Prices • May 20, 2026

Are Home Prices Going To Fall?

It’s one of the biggest holdups some buyers have right now: “What if I buy, and home prices go down?”

With everything in the news, that concern makes some sense. No one wants to make a big financial decision at the wrong time. But here’s what’s important to know. You don’t want to get hung up on the few places seeing slight declines right now.

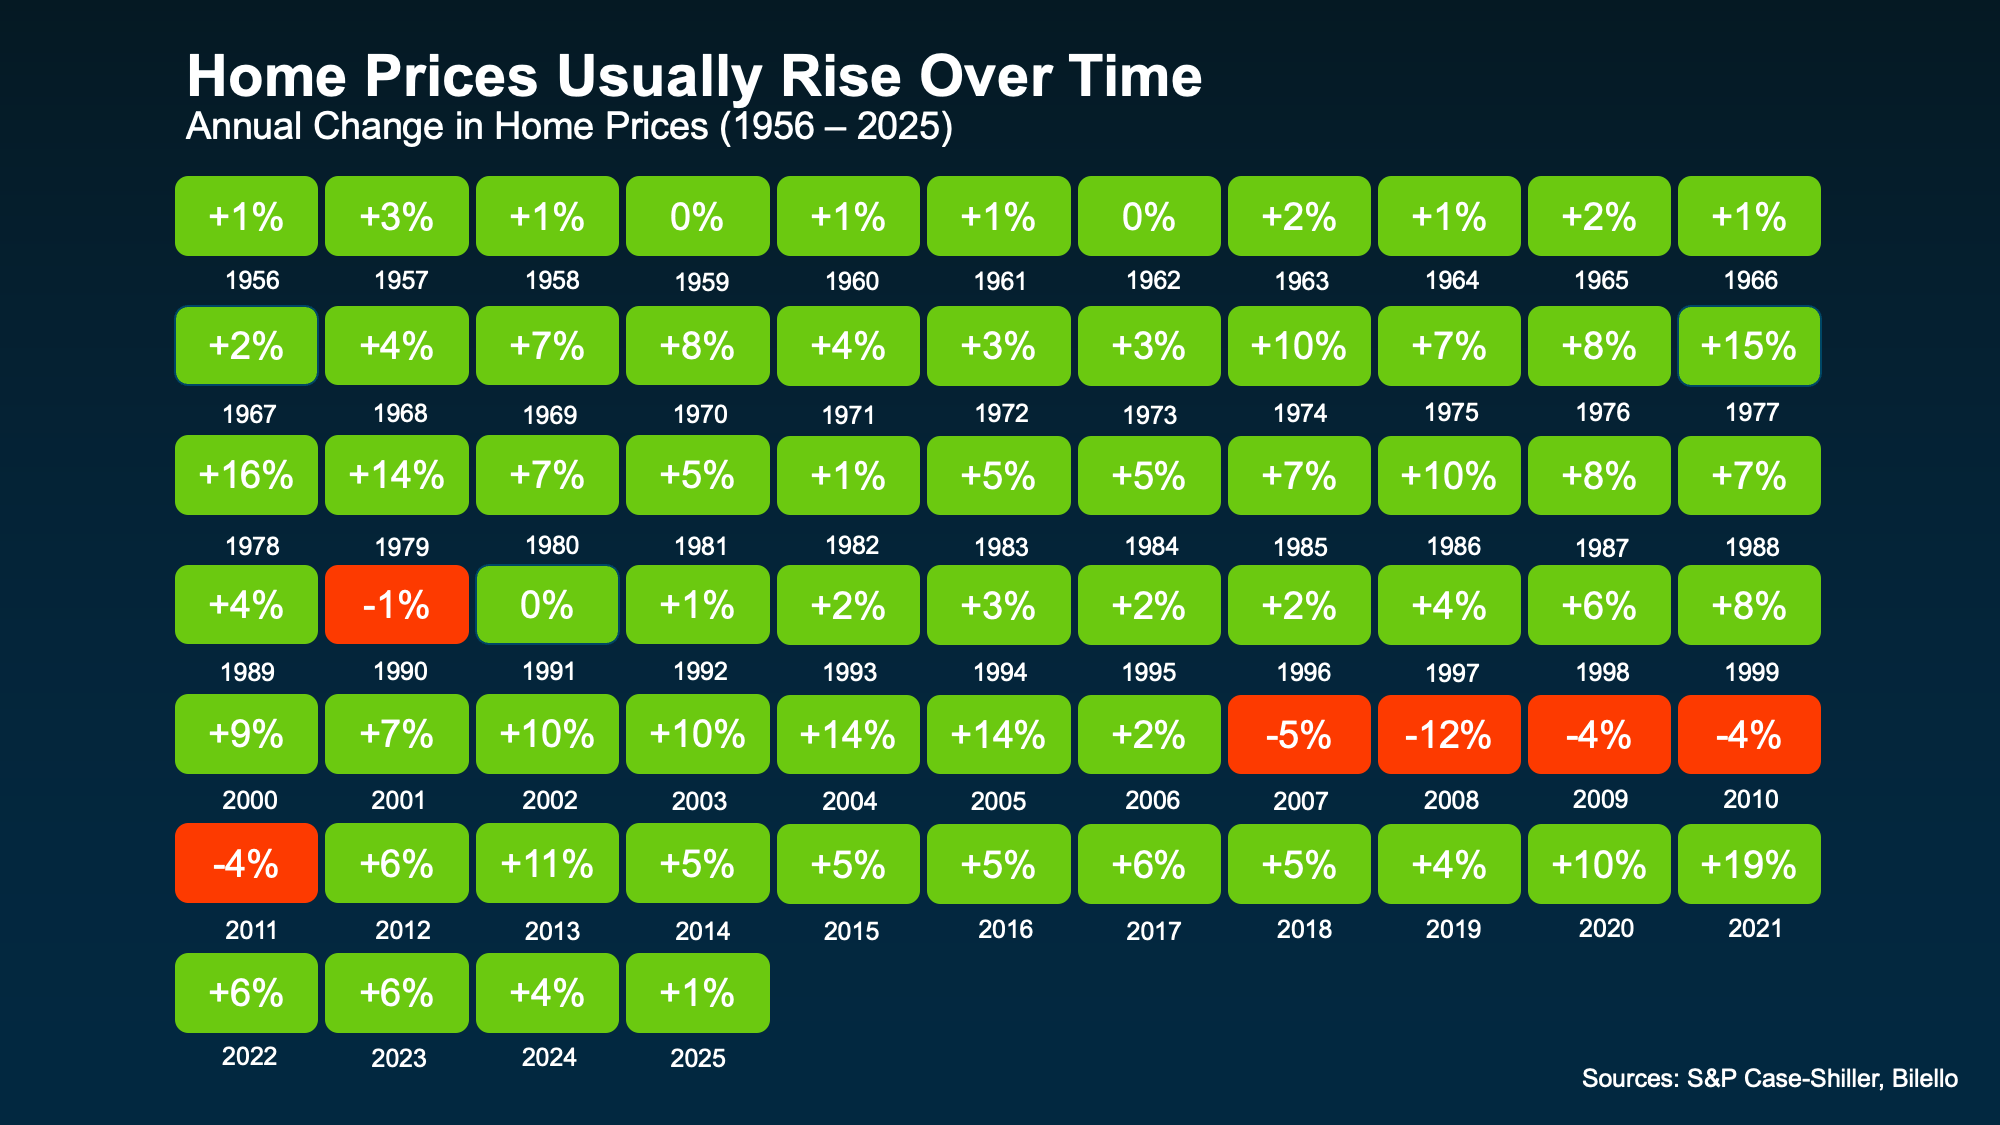
When you zoom out and look at the full picture, home prices usually rise over time.

What the Data Really Shows

Take a look at the visual below. It uses data from Case-Shiller and Bilello to show how home prices have changed year by year, going back to the 1950s.

Here’s the key takeaway.

Outside of the housing crash, home prices have either held steady or increased in just about every year for decades (see visual below):

a chart of percentages and numbersThat’s a remarkably consistent track record. And it shows something that many headlines miss.

While short-term shifts can happen, it’s the long-term gains that really matter.

Why Prices Tend To Rise Over Time

There are a few core reasons prices usually go up each year:

  • There are always people who need to move. People need a place to live, and that demand will never fully go away. It may ebb and flow, but someone will always have to move as big changes happen in their life. So, homes stay in demand.
  • There still aren’t enough homes for sale. While the number of homes for sale has grown, nationally, there’s still an undersupply based on how many people want a home. That keeps upward pressure on prices.
  • Inflation has an impact. Over time, the cost of goods (including homes) naturally increases. That pushes home values higher.

What That Means for You as a Buyer

It’s easy to get caught up in what might happen with home prices next month or next year, especially if you’re a first-time buyer and you’re feeling a little anxious about making such a big financial commitment. But the big picture is clear. Prices usually rise.

That doesn’t mean prices will go up every single year in every market. Real estate is local, and there can be short-term ups and downs. We’re seeing that in some places right now. You can even see it in the few annual dips in the visual above.

But historically, the declines have been temporary.

That’s why it’s generally recommended to buy a home only if you plan to stay for a while – typically at least five years. That’s normally enough time to see your house grow in value. And it’s enough to ride out any short-term changes in the market.

Because when you can do that, something powerful happens. Those rising home values grow your net worth, and by extension, help you build wealth.

The right decision isn’t about timing the market perfectly. It’s about making a move that works for your life and staying in it long enough to benefit from the bigger trend.

Bottom Line

Home prices have a long track record of going up over time. And that’s why buying a home is generally considered a safe long-term investment.

That certainly doesn’t mean you have to buy now. You should only move when it makes sense, and you plan to live there for a while.

But if you’re interested, let this reassure you. If you want to talk through what’s happening with home prices in our market, your goals, or your timelines, let’s have a quick conversation.

For Buyers • May 6, 2026

4 Ways To Give Your Offer an Edge This Spring

Looking to buy a home this season? Here’s what you should know.

Buyers have more leverage today than they’ve had in years. There are more homes to choose from and, in many areas, sellers are more open to negotiation.

But that doesn’t mean competition is gone completely. These days, it varies a lot depending on where you’re hoping to move.

If you’re buying in a popular neighborhood or in a market where there aren’t many homes for sale, you may still find yourself competing with another buyer.

And that’s especially true in the Spring. Here’s how to stay one step ahead of any competition this season.

Why Your Best Offer Still Matters This Spring

According to experts at Zillow and Realtor.com, Spring is one of the busiest times of year to buy a home.

That’s because many buyers want to move now so they can settle in before the next school year. And when more buyers enter the market, competition naturally picks up.

So, depending on where you’re buying, you may still need to move quickly and make a strong offer, even though the market overall has moderated. And that’s especially true if you find a home you really love.

This is what you need to know to make your offer stand out.

1. Lead with a Strong, Realistic Offer

It’s tempting to start low and negotiate up. And in some markets, that strategy can work. But if a home is priced well and getting attention, lowballing could hurt your chances.

Instead, focus on making an offer that reflects your local market. As Bankrate explains:

“There is no magic formula for an optimal home offer. Any offer will be heavily dependent on asking price and local market conditions . . . Your real estate agent will know the local market well and can advise what a competitive — but fair — offer will look like in your area.”

The goal is to make an offer that makes sense for you and stands out to the seller.

2. Have a Plan for Competing Offers

If you’ve fallen in love with a home, it’s important to have a plan in case there’s competition from another buyer. One strategy your agent may discuss with you is an escalation clause, which Investopedia explains like this:

“An escalation clause is a way to automatically escalate your bid by a certain dollar amount, up to a certain ceiling, to compete with other bids.”

The key is knowing your budget and sticking to it. You don’t want to lose out over a small difference – and this can help prevent that. But you also don’t want to overpay.

Keep in mind that if the appraisal comes in lower than your offer, you may have to make up the difference out of pocket. Your agent can help you weigh those risks and determine the best approach for your situation.

3. Keep Your Offer Clean

Price matters. But sellers also look closely at your offer’s terms. In some cases, a simpler, cleaner offer can stand out – even if it’s not the highest. As Redfin says:

“Sellers tend to want clean, straightforward offers with minimal strings attached. Keep your requests simple and focus on the essentials.”

Your agent can help you prioritize what matters most, so you’re not giving up things you need, while still making your offer as appealing as possible.

4. Be Flexible Where You Can

Sometimes, what helps your offer the most is understanding what matters to the seller. NerdWallet explains:

“As you prepare an offer, you tend to focus on what the seller has (a house) and what you want (their house). But you’ll gain a competitive edge by viewing the transaction from the seller’s eyes: What does the seller want?”

Does the seller need extra time to move out? Or do they want to move as soon as possible? Your agent can talk with the seller’s agent to find out what matters most. Flexibility here can make a big difference in how your offer is received.

Bottom Line

Today’s market may be balancing out, but strong offers still matter – especially during the busy Spring season.

Curious how competitive things are (and what it’ll take to win) in our market? Let’s talk.

For Buyers • For Sellers • Forecasts • Home Prices • Mortgage Rates • April 29, 2026

3 Things That Are Not Going To Happen in Today’s Housing Market

There’s a lot of uncertainty right now, and that’s leading to some dramatic headlines. And if you’re thinking about buying a home, that can make you feel a little less sure about your decision.

A recent study by CNBC asked homebuyers what they’re most worried about, and three themes kept coming up again and again:

  • Mortgage rates
  • The number of homes for sale
  • Home prices

But a lot of what you may be hearing on those is based more on misconceptions. Not facts. So, let’s break it down and separate fact from fiction.

Misconception #1: “I’ll Just Wait, Because Mortgage Rates Are Going To Fall Dramatically”

One idea doing its rounds on social is that mortgage rates are going to drop dramatically soon. So, it’s better to wait to buy.

But is that really what’s expected?

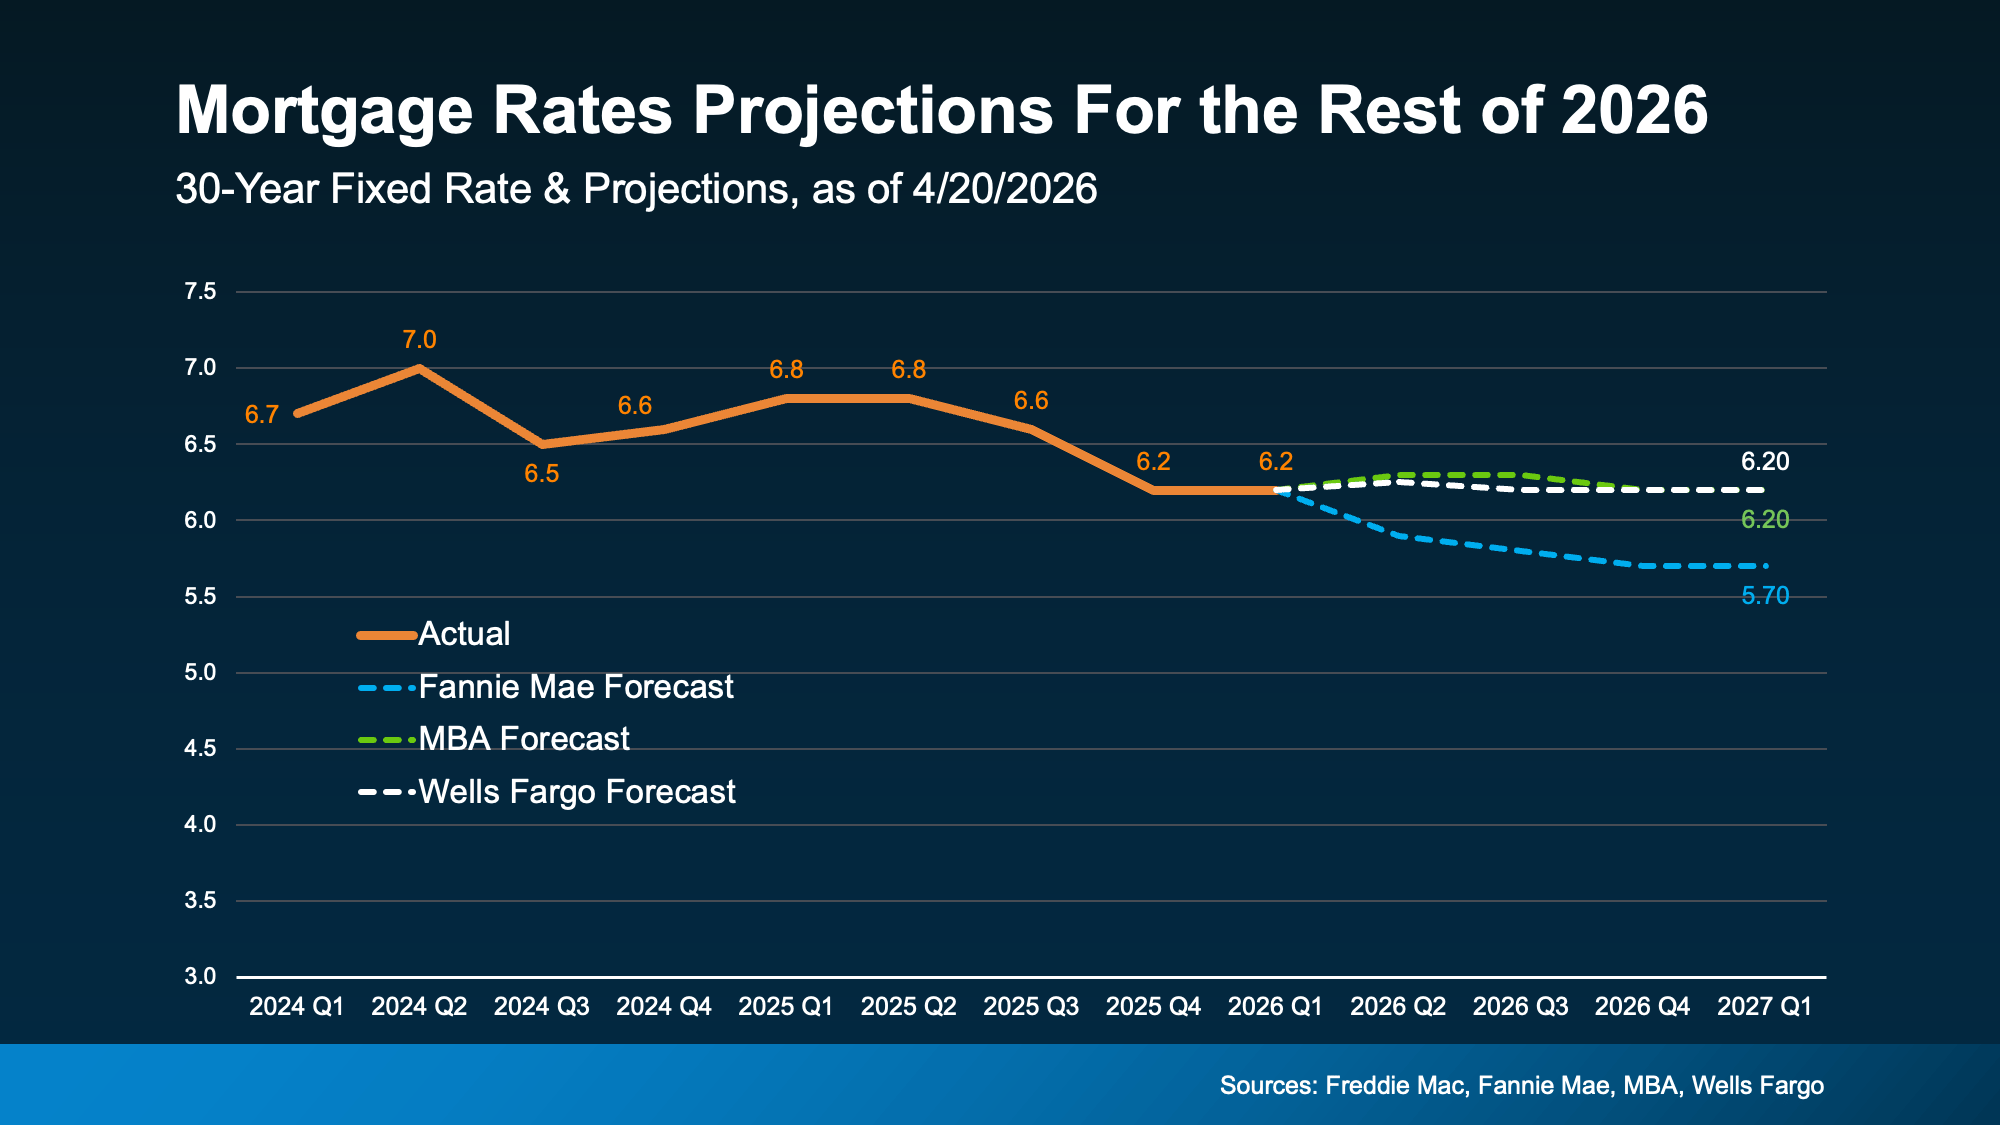
While mortgage rates have come down a bit in the last few weeks, forecasts don’t show a major drop ahead. The most likely scenario is that rates stay somewhere in the low 6% range this year.

And that’s not a big change from where rates are now (see graph below):

a graph with numbers and linesOf course, this depends on where inflation and the economy go from here. But, based on what we know today, waiting for a big drop in rates may not work out the way some people hope. As U.S. News explains:

“Mortgage rates aren’t expected to change much over the next several quarters . . .”

Not to mention, even with rates where they are today, it’s already more affordable than a year ago. So, even if they don’t change much, it’s still better than it was.

Misconception #2: “There Are Too Many Homes for Sale Right Now”

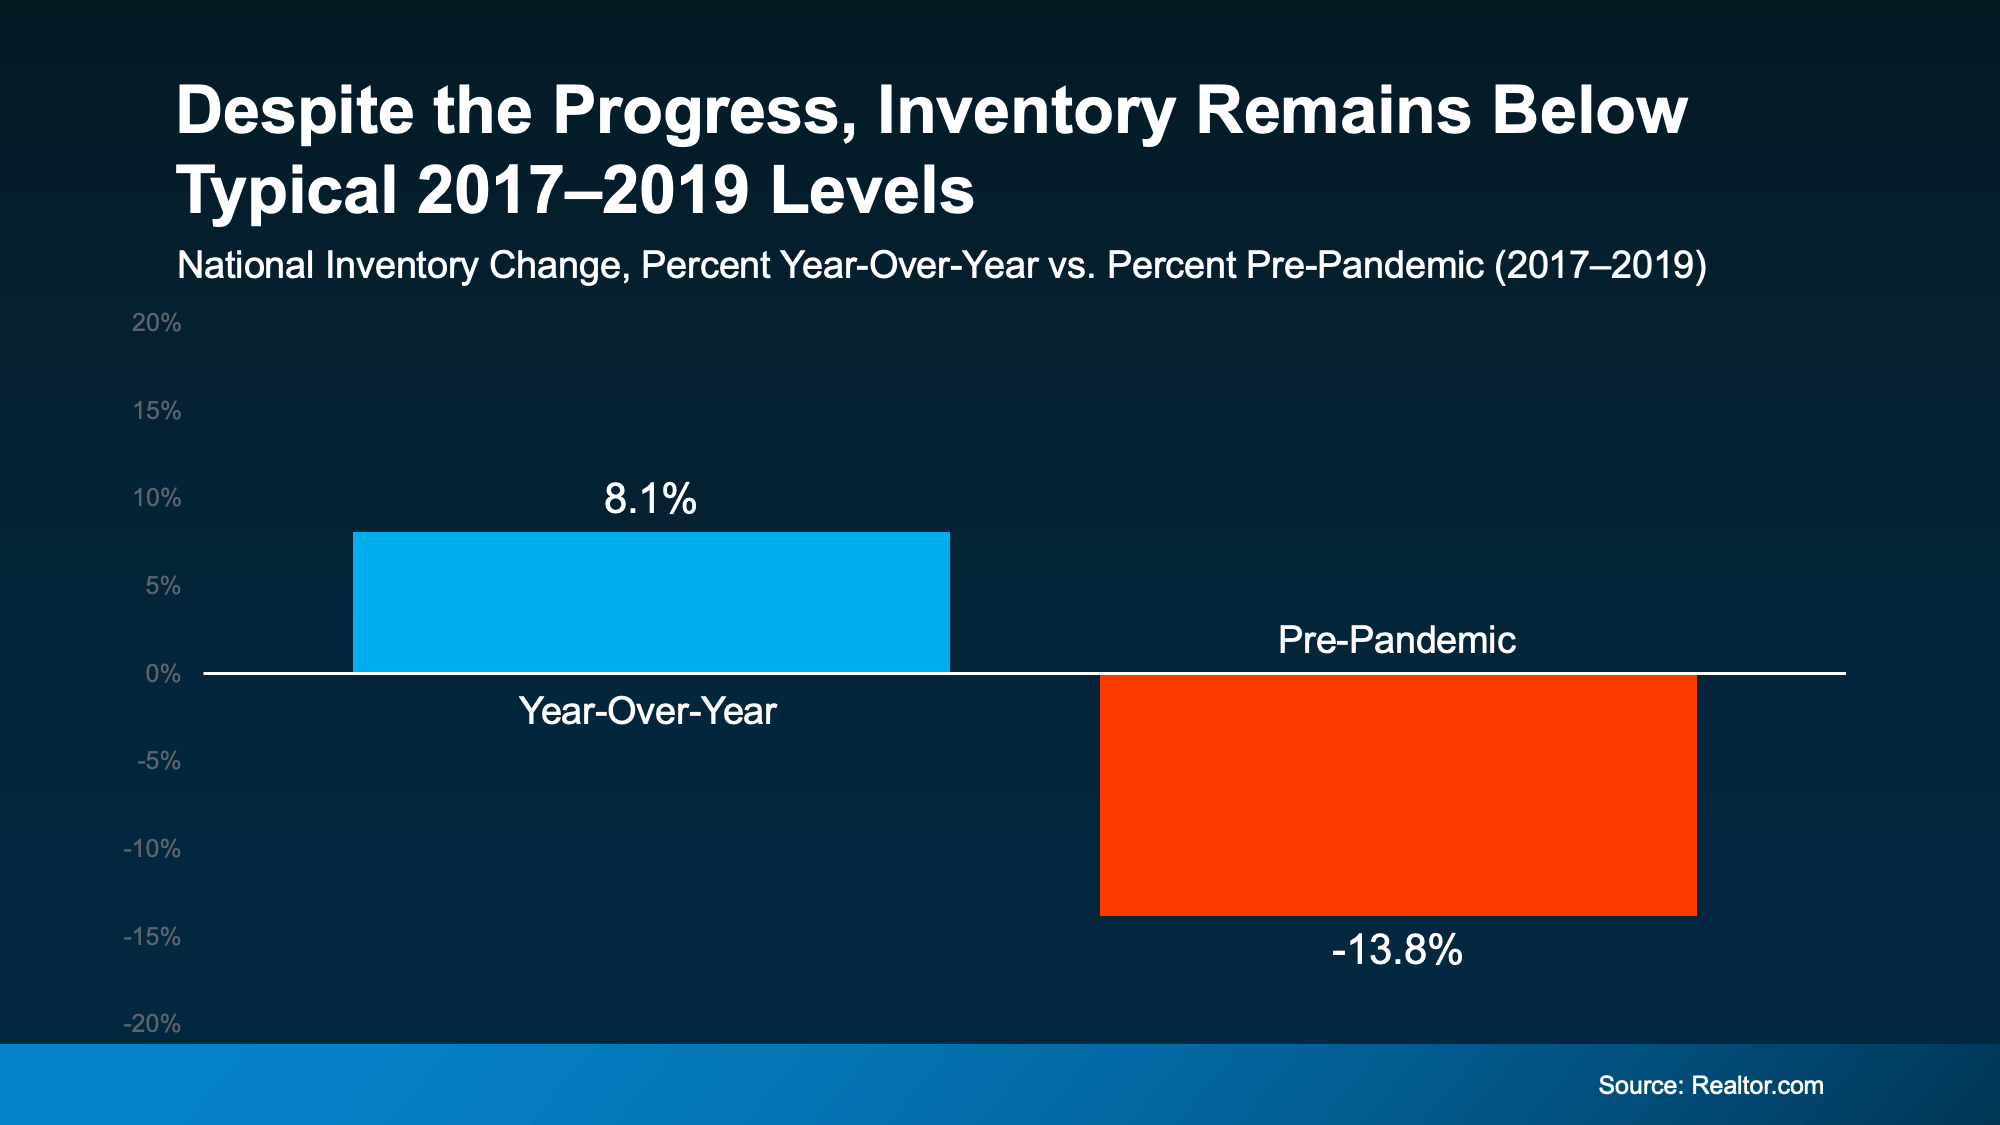
You’ve probably heard inventory is up. And nationally, it is. The number of homes for sale is 8% higher than this time last year. But that’s not a bad thing. In fact, it’s one of the reasons buyers have a bit more breathing room right now.

The problem is the headlines are making something good, sound bad. They’re focusing on how this is the most inventory we’ve had since 2019 or how many homes builders are building. And that can make it sound like the number of homes for sale is rising too far, too fast.

But that’s not what the bigger picture shows.

Data from Realtor.com proves that, even though inventory is up compared to last year, it’s still nearly 14% lower than it was during the last normal housing market (2017-2019):

While it can vary a lot based on where you live, only 9 states have more inventory than pre-pandemic today. That’s a key reason why there still aren’t enough homes for sale to trigger something like the crash back in 2008.
Misconception #3: “Home Prices Are About To Crash”

You’ve probably seen this one, too. The confusion is coming from the fact that some metros are experiencing slight price declines. And influencers are running with that and saying prices are crashing. But that’s not the reality.

Most areas are seeing prices rise, not fall. And that’s because:

  • Many homeowners aren’t selling because they don’t want to give up the low mortgage rate they locked in a few years ago. And that’s keeping a lid on how much inventory can grow.
  • Since inventory is still below pre-pandemic norms, there aren’t enough homes for sale to cause a price crash.
  • And even in markets with more inventory, some sellers are choosing to pull their homes off the market instead of cutting prices.

And those are 3 big reasons prices aren’t headed for a crash. 

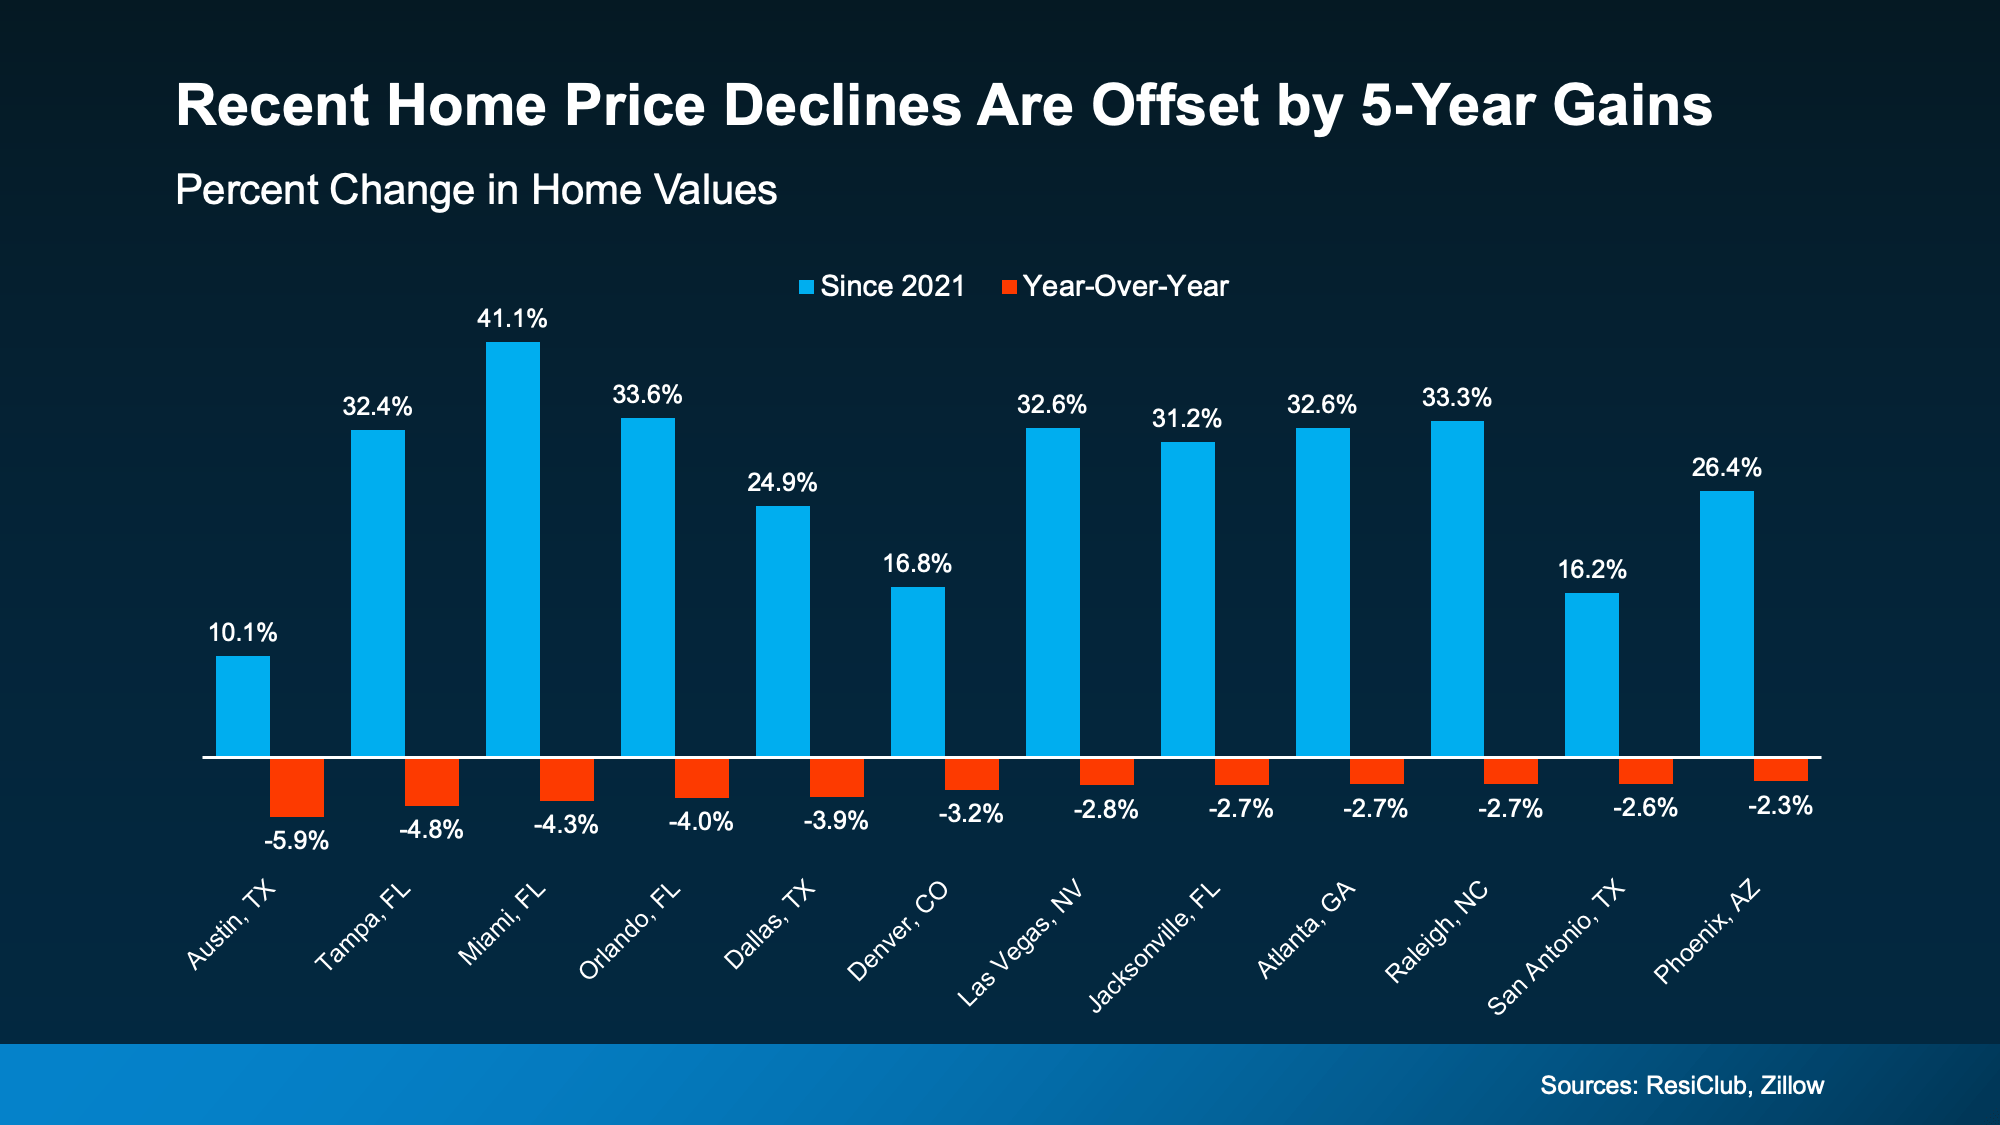
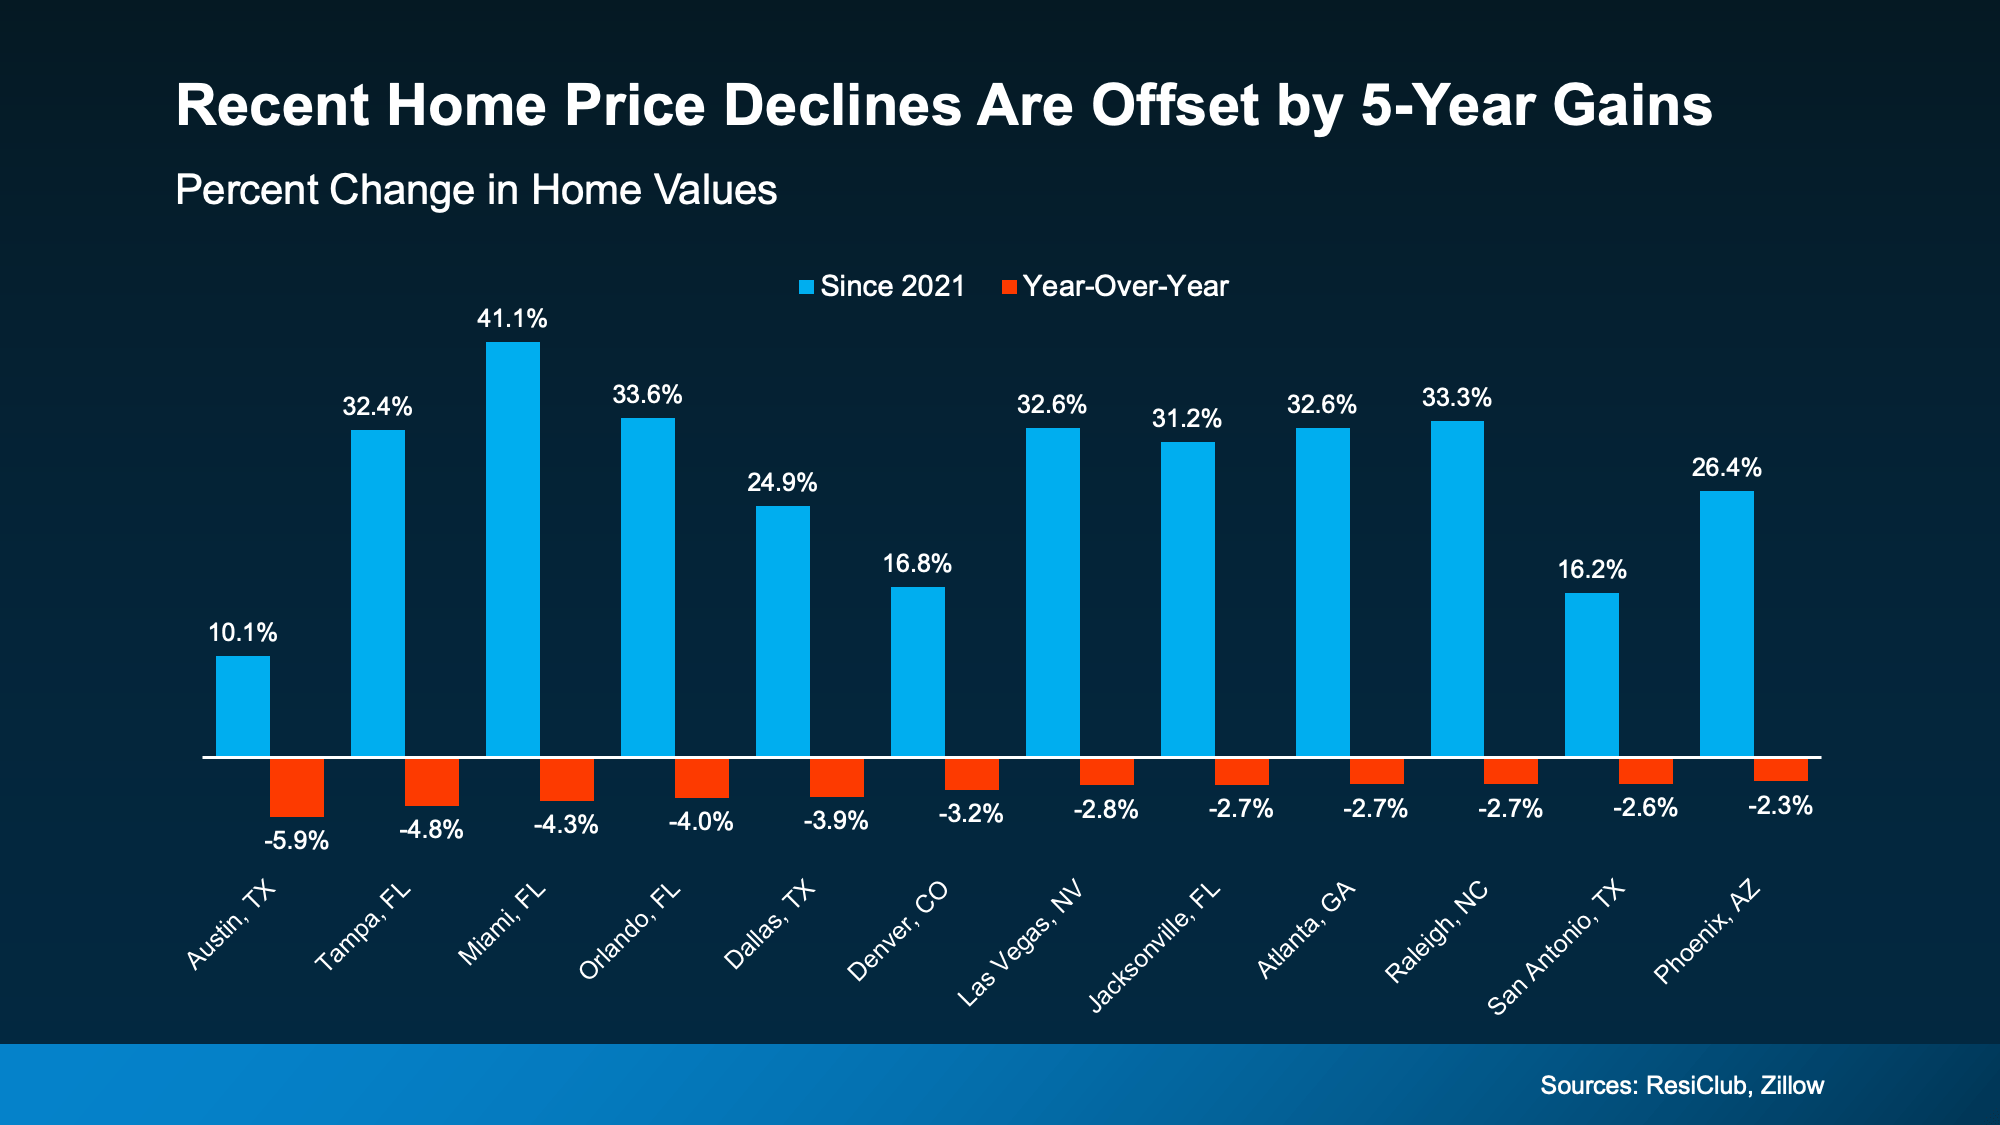
And even in the markets experiencing mild declines, the drops aren’t enough to cancel out the big gains most homeowners have seen in the last 5 years (see graph below):

That’s not a crash. That’s just prices moderating after a few record-breaking years.
Bottom Line

Online posts are going to make things sound worse than they are. If you want a true, data-bound look at what’s really happening in today’s market, lean on a real estate agent.

Let’s connect so you have someone to separate fact from fiction today.

For Buyers • Home Prices • April 22, 2026

Rent or Buy? The Real Tradeoff Most People Don’t Talk About

You’ve probably asked yourself lately: Is it even worth trying to buy a home right now? It’s a question a lot of people are asking.

With today’s home prices and mortgage rates, renting can feel like the easier path. In some cases, it might even seem like the only realistic option right now. And if that’s where you are, there’s nothing wrong with that.

But if you’re weighing the decision, there’s one part of the conversation that doesn’t get talked about enough.

It’s what each choice does for your future.

What Renting Really Gets You (And What It Doesn’t)

Depending on your situation, renting does have some advantages:

  • Lower upfront costs.
  • Less responsibility.
  • More flexibility to move when you want.

But even with those benefits, a Bank of America survey found 70% of aspiring homeowners worry about what long-term renting means for their future. And that concern comes down to one thing: you’re not building anything for your future. As Yahoo Finance explains:

“Paying rent doesn’t build equity. You get a place to live, but no ownership stake, no price appreciation, and no asset to leverage for future borrowing or investment.”

So, while renting may feel easier, the flexibility you get comes at a cost.

How Homeownership Builds Your Wealth Over Time

On the other hand, owning a home is one of the most consistent ways people build wealth over time. Why? When you’re a homeowner, you gain something called equity. That’s the difference between what your home is worth and what you owe.

That equity grows with every monthly payment you make. It also gets a boost as home values go up through the years – and it adds up quicker than you may think.

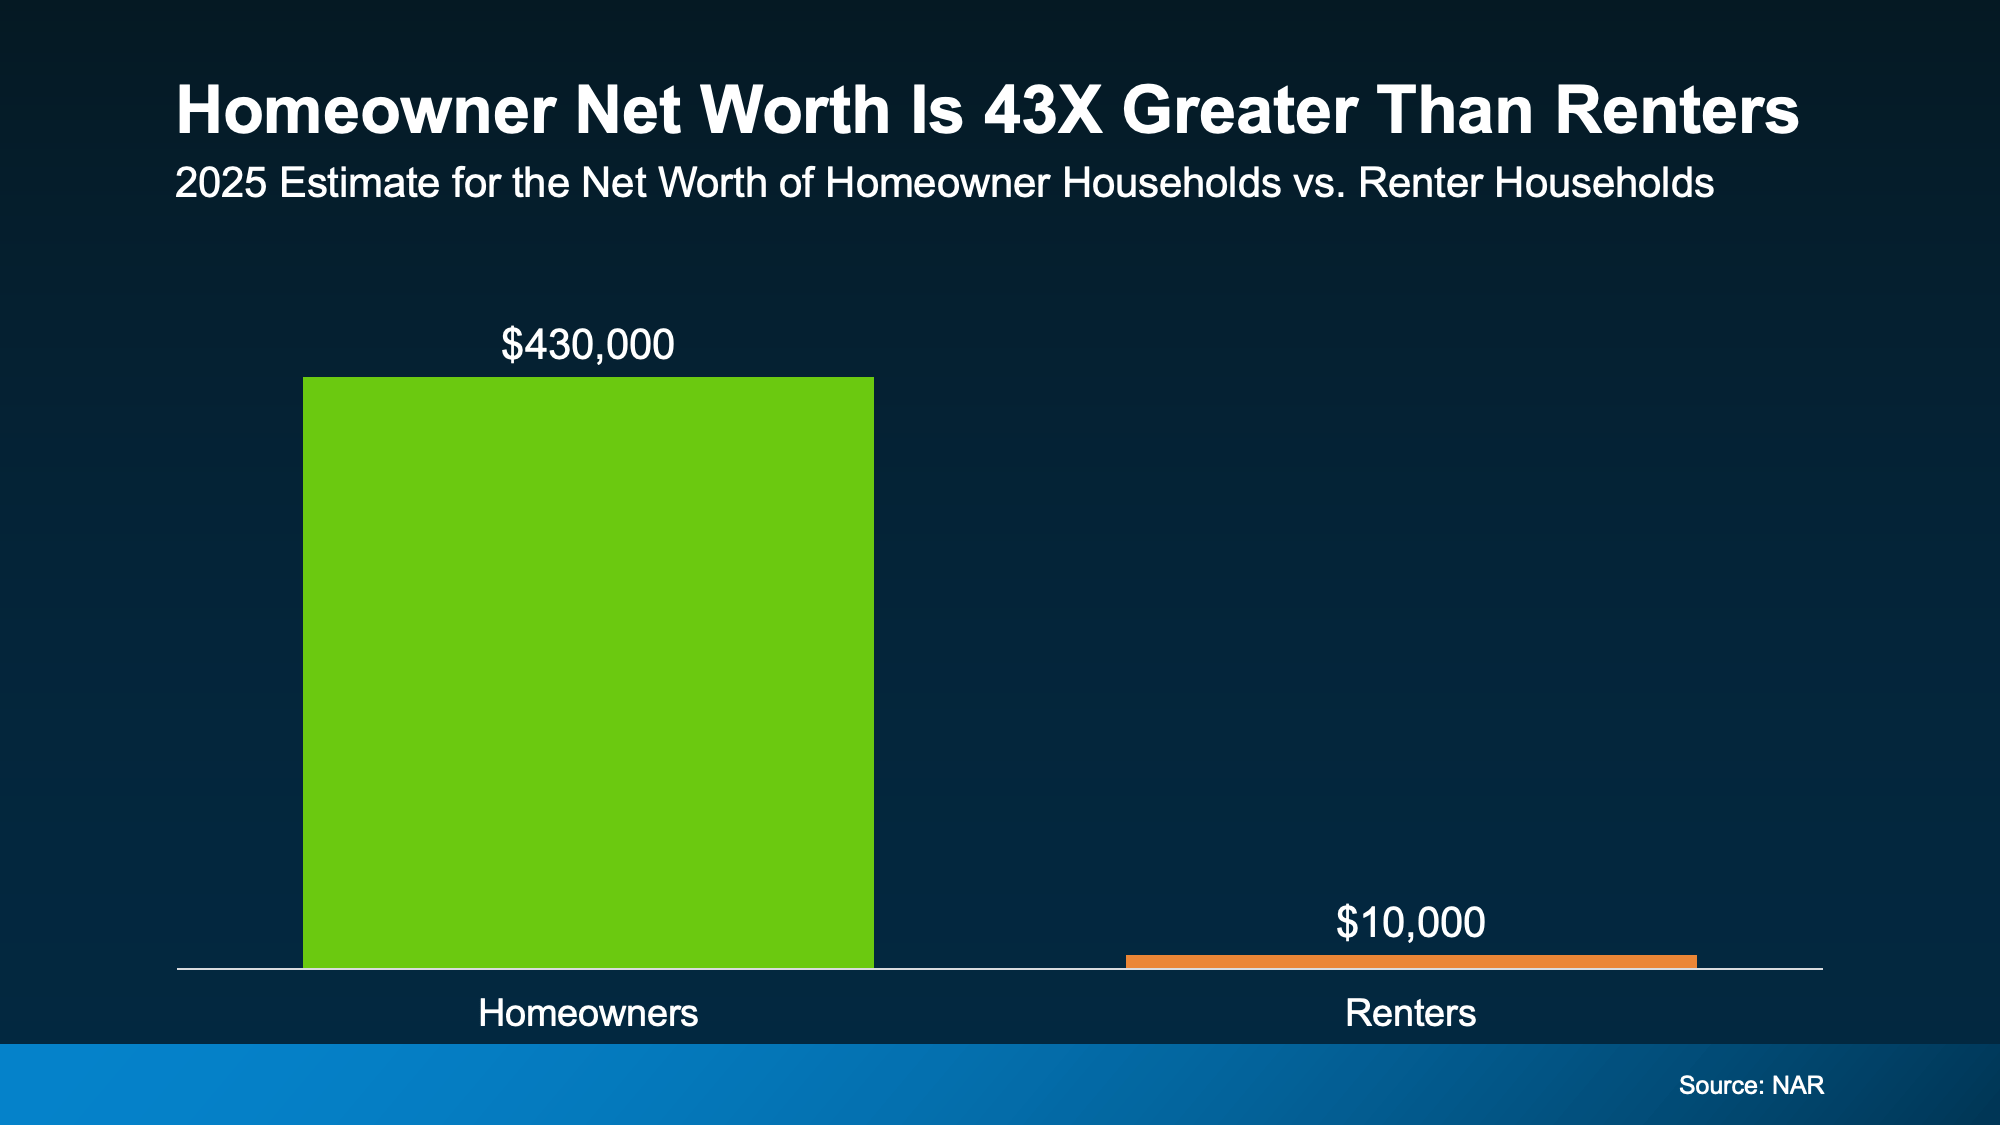
Today, the National Association of Realtors (NAR) says the average homeowner’s net worth is 43X greater than that of a renter:

a graph of a number of peopleThe dollars in the visual don’t lie. On average, here’s how net worth compares:

  • Homeowners: $430k
  • Renters: $10k

And it’s not because homeowners make wildly different decisions day to day. It’s because over time, one path builds something, and the other doesn’t.

So sure, buying comes with some upfront costs and more responsibility. But it’s basically a savings account you can live in.

The Gap Is Growing Over Time

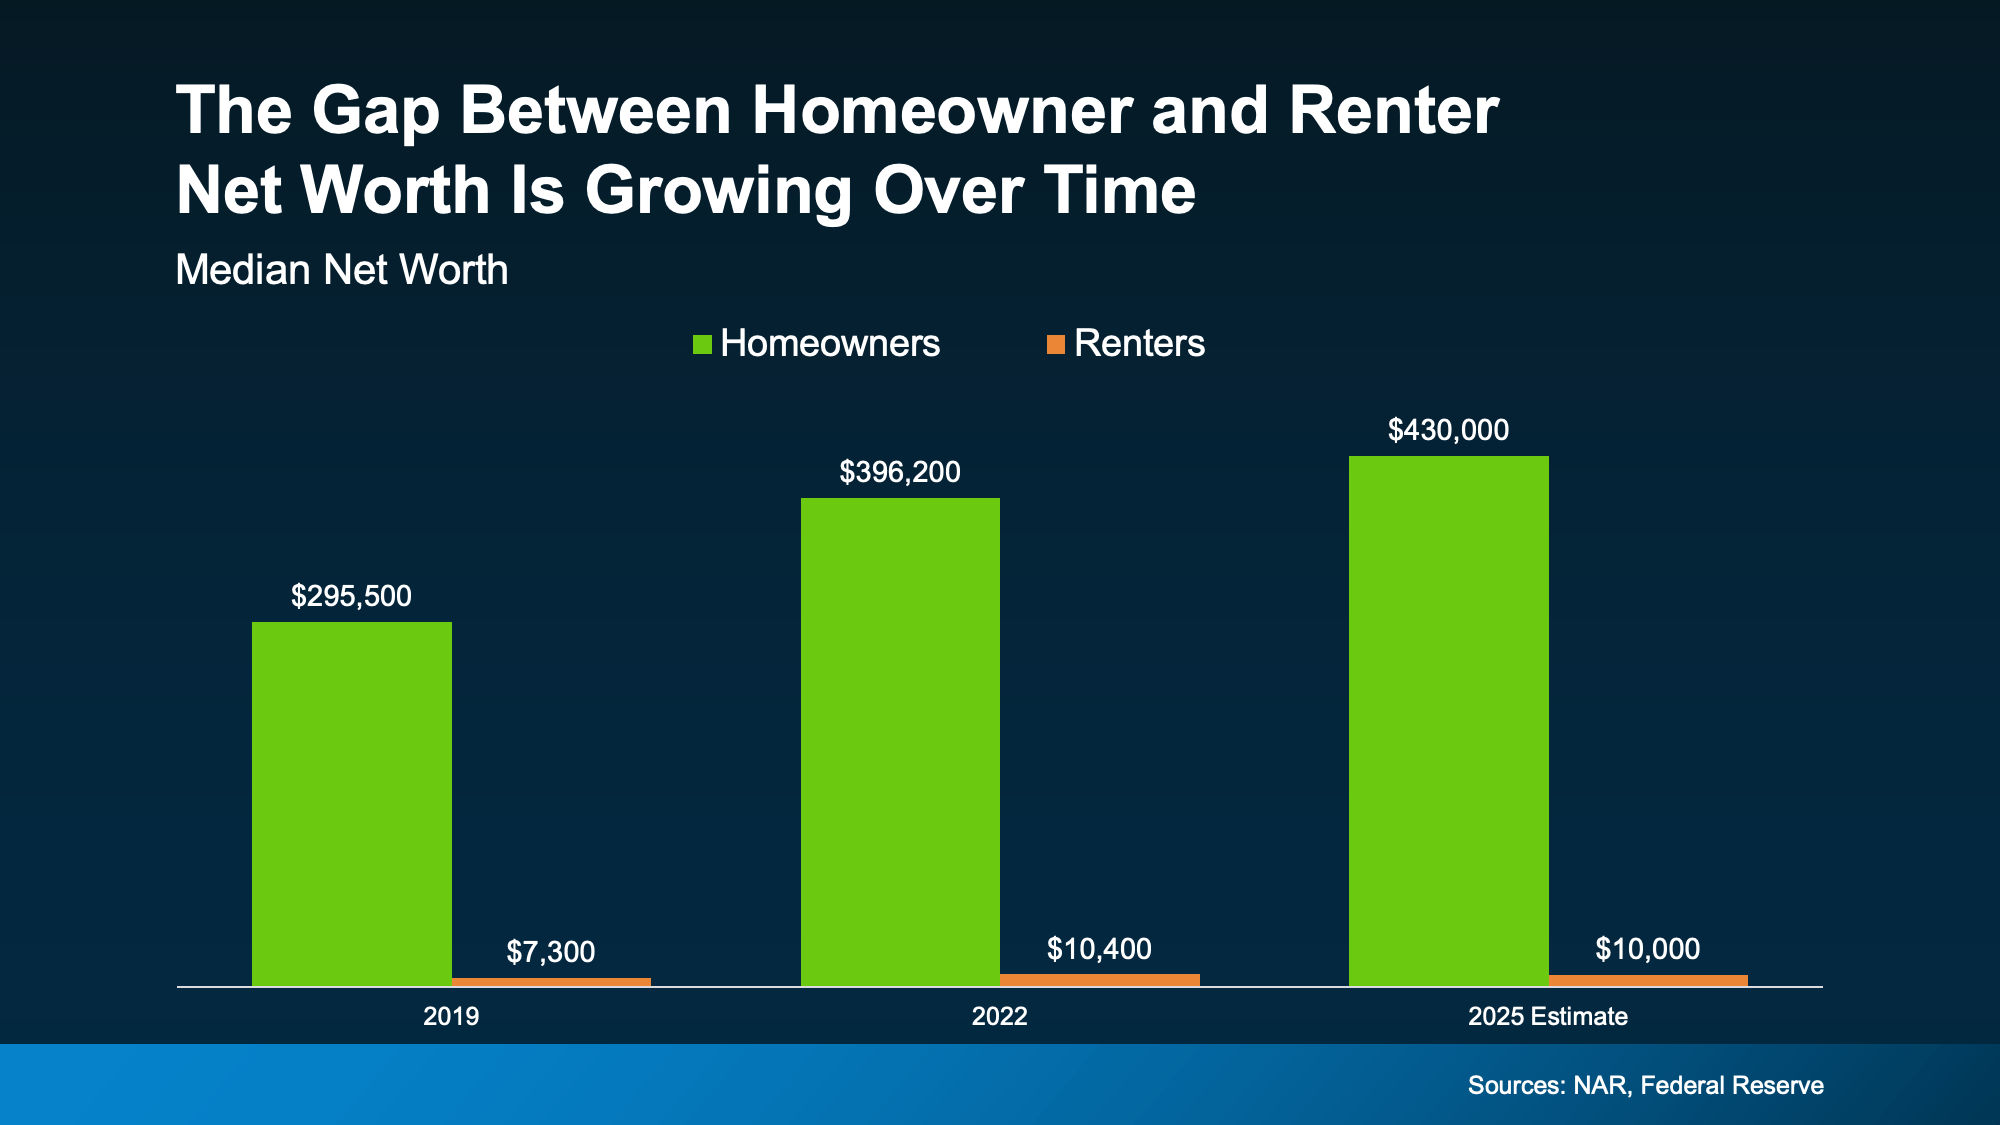
And here’s something else interesting. That net worth gap between renters and homeowners has been widening over time, not shrinking.

If you look back at the reports on net worth through the years, you can see the gap is growing as homeowners gain wealth and renters stay stuck in the rental trap (see graph below):

a graph of green and blue barsEven in 2025, when home prices were moderating, homeowners still gained even more ground. And that tells you something important:

When you can afford it and you’re ready for the responsibility, history shows buying is usually worth it in the long run. Because either way, you’re paying for someone’s mortgage and building someone’s net worth.

When you rent, it’s your landlord’s mortgage – not yours. But when you buy? Your monthly payments help build equity.

The question is: whose do you want to pay? Yours or theirs?

So, Should You Buy a Home Now?

The short answer is, it depends on your situation.

While the long-term benefits of buying are clear, that doesn’t mean the timing is right for everyone right now. And that’s okay. You should only buy a home once you’re ready and the numbers work for you.

But whether you’re looking to buy now or planning for the future, the first step is the same. You should have a quick conversation with a local real estate agent about your goals, timeline, and budget.

They can help you run the numbers and see what’s realistic. You may find buying is closer than you thought. And if not, you’ll at least know exactly what it will take to get there.

Because the sooner you have a plan, the sooner you can decide when it makes sense, instead of wondering if it ever will.

Bottom Line

Renting may feel more do-able today. But over time, it could cost you.

If you want to ditch renting and start building something for your future, it starts with a simple conversation. Let’s connect, talk about your specific goals, and explore your options – so you’re ready when the time is right for you.

For Sellers • April 10, 2026

Your House Hasn’t Sold Yet. Should You Rent It Out Instead?

When your house sits on the market longer than expected, it can get frustrating fast.

You start asking: what now? And for a growing number of homeowners, that turns into: should I just rent it instead?

While it sounds like a simple backup plan, becoming “accidental landlord” is actually a much bigger decision than most people realize. That’s when someone planned to sell, didn’t get the price or traction they hoped for, and decided to rent the house out instead.

And lately, that’s happening more often.

Why the Number of Accidental Landlords Is Rising

If you’re faced with the same choice to rent or to sell, here’s what you need to know. First, you’re not alone. And that should actually be some comfort.

According to Zillow about 2.3% of homes available for rent were previously listed for sale. That may not sound like a lot, but it’s actually the highest share in almost 6 years.

Before you go that route yourself, it’s worth slowing down and looking at the full picture. Ask yourself these 3 questions first.

1. Would Your House Actually Work as a Rental?

What’s right for your situation is going to depend on your location, your home’s condition, and what the rental market looks like in your area. Think about:

  • If you’re moving away, do you have a plan for how you’ll handle ongoing maintenance and repairs from afar?
  • Does your house need repairs before it’s rental-ready? And do you have the time, energy, and the funds for that?
  • What’s the market like in your area? Are there a lot of rental vacancies?
  • What monthly rent could you realistically expect?

As C&C Property Management explains:

“At the heart of any rental market is the balance between supply and demand. When more tenants are looking for housing than there are available units, rental prices rise. On the other hand, if new construction adds hundreds of apartments or homes to a neighborhood, prices can soften as tenants have more choices.”

If your home would struggle to stand out or command the rent you need, that’s something to take seriously. Just because you can rent it doesn’t mean it’s the best option for you.

2. Are You Ready To Be a Landlord?

This is the part people don’t always think about upfront. On paper, renting sounds like easy passive income. But in reality, it’s a hands-on responsibility. Imagine:

  • Taking midnight calls about clogged toilets or broken air conditioners
  • Chasing down missed rent payments
  • Covering unexpected repairs
  • Fixing damage between tenants

And those costs can hit when you least expect them.

3. Have You Run the Real Numbers?

There’s also the financial side of things. For starters, renting out your house comes with extra expenses. Here are a few of the biggest according to Bankrate:

  • Higher insurance premiums (landlord insurance typically costs about 25% more)
  • Management fees (if you use a property manager, they typically charge around 10% of the rent)
  • Routine maintenance and services
  • Advertising fees to find tenants
  • Gaps between tenants, where you cover the mortgage without rental income coming in

For some people, that’s totally manageable. For others, it’s more than they want to take on.

Your Next Step: A Conversation with Your Agent

Before you make any decision, talk to your current agent about overhauling your sales strategy first. Sometimes it’s not that buyers aren’t out there. It’s that something about the pricing, presentation, or marketing isn’t quite lining up with what they’re looking for.

And a few small adjustments can make a big difference.

Because while renting can be a great choice for the right person with the right house, if you’re only considering it because your listing didn’t get traction, there may be a better solution.

Bottom Line

If you’re torn between selling and renting, make sure to carefully weigh the pros and cons first. For some homeowners, the hassle (and the expense) of renting may not be worth it.

For Sellers • March 19, 2026

If Your House Isn’t Getting Offers, Read This.

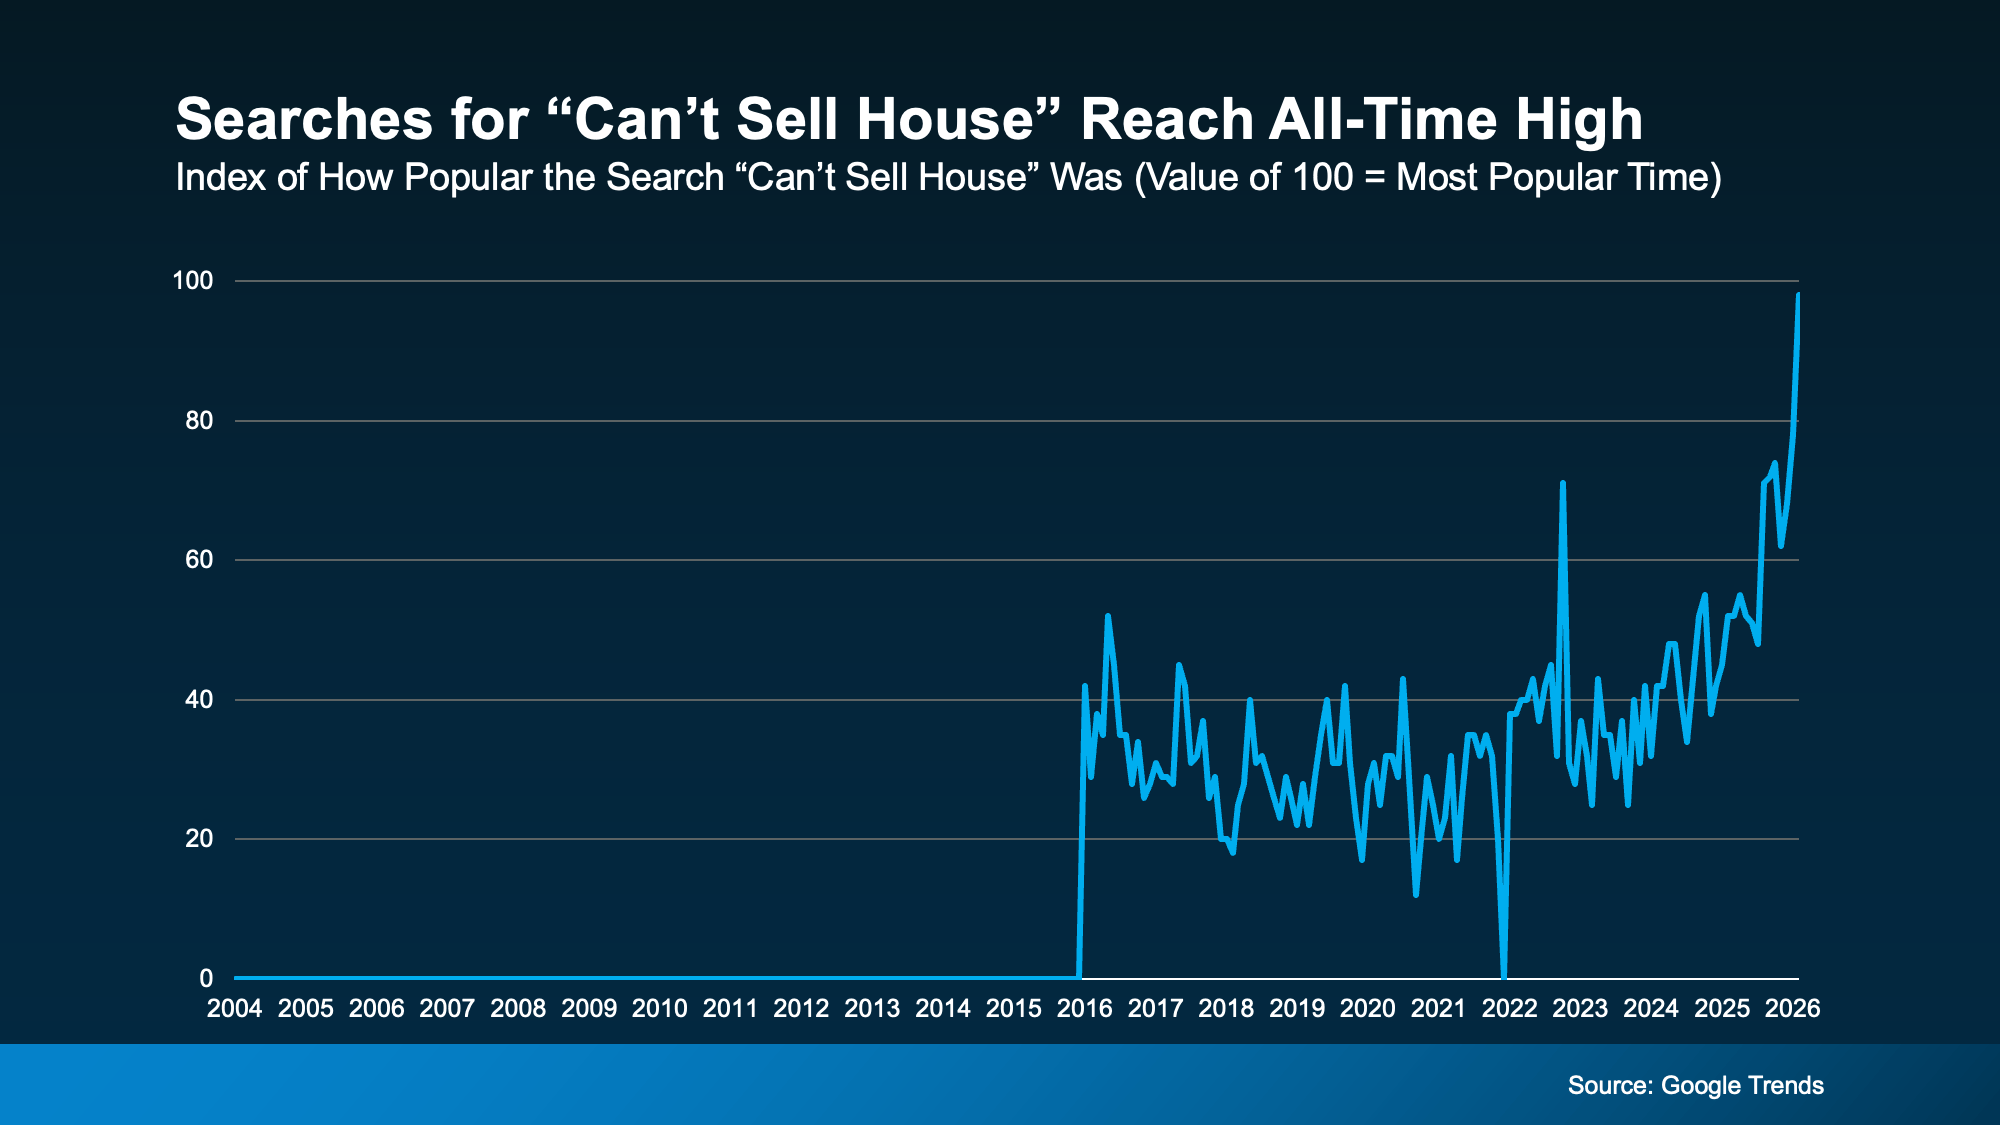
Online searches for “can’t sell house” just hit an all-time high according to Google Trends. So, if your house has been sitting on the market without any bites, you’re not the only one. But it’s also not the end of the road. 

Homes are selling every day, so you can turn this around. You just need to take another look at your approach.

a graph of a house priceIf you’re feeling this pain, know this: an online search engine isn’t where you should go for your answers. It’s much better to talk to your agent. Because a search engine doesn’t know your market or your house. But your agent does.

While a quick search or an AI platform may give you some tips on what to try, only an expert agent can actually diagnosis what’s going on – and how to fix it.

For example, your agent knows most homes that struggle to sell today are usually being held back by one (or more) of these three things.

1. Presentation: Buyers Will Compare Everything

When inventory was tight a few years ago, buyers overlooked imperfections because they had to, or they’d lose out to another bidder. Now? That’s no longer the case.

Today’s buyers scroll through dozens of listings in just minutes. They compare condition, updates, lighting, finishes, layout, and more – all side by side. If your home feels dated, cluttered, or in need of repairs, buyers will notice and it’ll knock your house right off their list of contenders.

This doesn’t mean you need a full renovation. But it does mean first impressions matter again. To compete today, you need curb appeal. Clean spaces. Neutral colors. Professional photos. If there are scuffs on the walls, obvious repairs, or too many outdated features, it could be what’s holding you back.

2. Pricing: If the Price Isn’t Compelling, It’s Not Selling

This is maybe the hardest one to hear, but what your neighbor sold their house for a few years ago isn’t necessarily the same price you’ll get today. As Selma Hepp, Chief Economist at Cotality, says:

“For sellers, the days of pricing aggressively and expecting instant offers are largely over. Homes that are well-priced and well-presented will still sell, but pricing discipline matters more than it did during boom years.”

Buyers are budget-conscious right now. If your home is priced based on outdated expectations instead of current demand, buyers may still look at your house online… but they likely won’t write an offer. Or, they’ll make an offer that you think is too low.

Pricing too high for this market is one of the top things sellers miss the mark on today. And those who aren’t willing to meet the market where it is or entertain offers may feel stuck.

3. Access: If Buyers Can’t See It, They Can’t Buy It

It sounds obvious but limited showing availability can kill your momentum. If your house isn’t easy to see because you’re restricting showings to evenings only, no weekends, or requiring a 24-hour notice, you’re cutting your buyer pool down by more than you may realize.

And the more friction you create, the fewer buyers walk through the door.

In a market where buyers have more options, the last thing you want to do is give them a reason to skip your house. Availability matters because if no one sees it, no one buys it.

Don’t Let Search Results Decide Your Next Step

When your house isn’t selling, it’s tempting to spiral and wonder if it’s the market or if something’s wrong with your house. But instead of searching for answers online, here’s what to do.

Sit down with your agent and ask three honest questions:

  • What are buyers looking for in today’s market?
  • What feedback are we getting from showings?
  • Why do you think my house hasn’t sold yet?

That conversation will bring a lot more clarity than any search engine results.

Bottom Line

If your listing feels stuck, it’s not a sign you shouldn’t sell. It’s the market giving you feedback. And feedback is powerful when you use it.

Start with a real conversation with a real agent about what’s working and what’s not. Your agent will be able to tell you which small adjustments could totally change the momentum. Because in this market, the sellers who adapt are the ones who move.

For Sellers • Home Prices • March 7, 2026

Are Home Prices Dropping? Here’s the Real Story.

You’ve probably seen posts on social media talking about how “home prices are falling.” And when you see something like that, it’s normal to wonder:

Is this the start of a crash?

What does this mean for my house?

Let’s clear this up right away. This is not a crash. And your home is not suddenly losing a lot of value.

The National Story – Prices Are Still Going Up

Here’s what often gets left out of what you’re seeing online. While some markets are experiencing slight declines, they’re the minority. Most places are still seeing prices rise or at the very least, hold steady.

That’s why, at the national level, home prices are still rising, just at a slower pace. According to the National Association of Realtors (NAR):

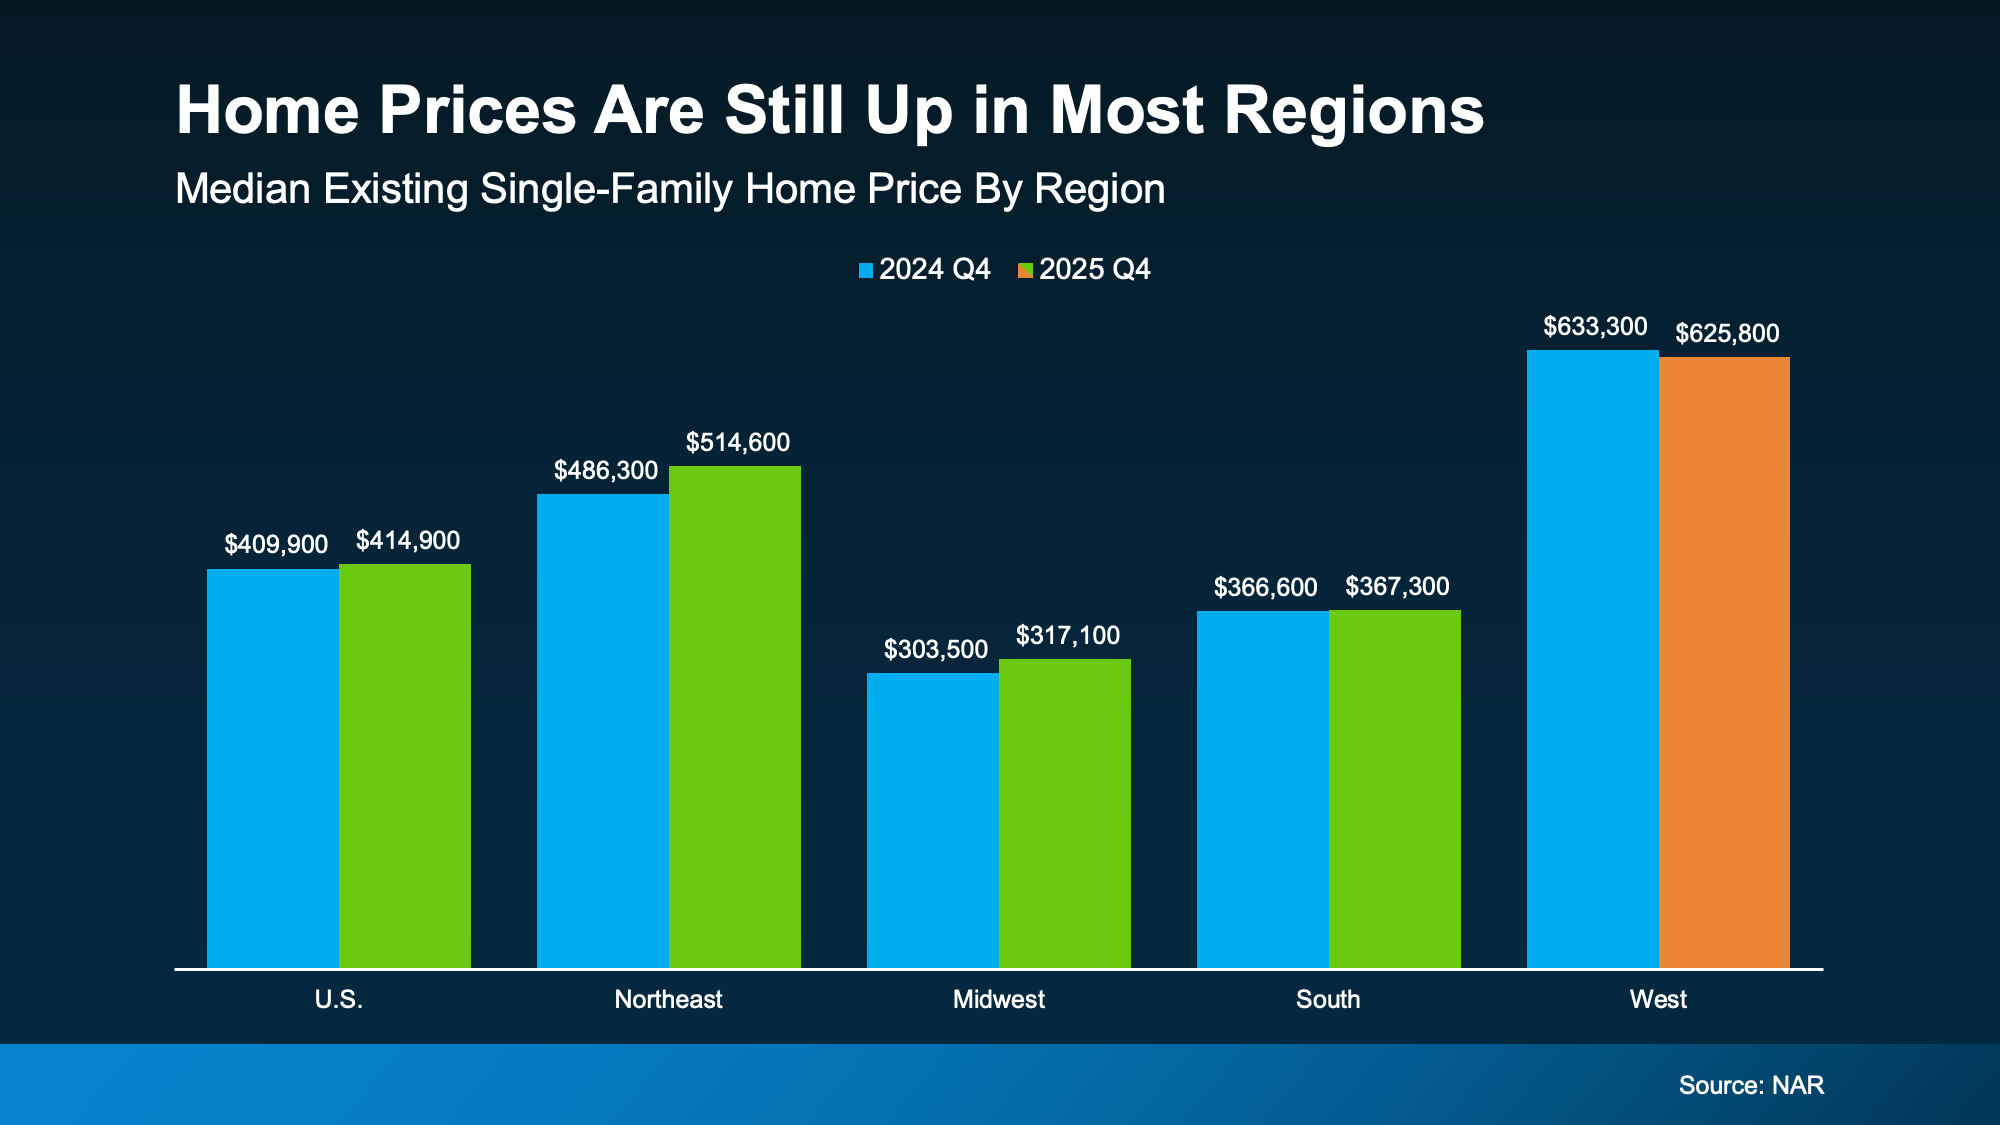
“Home prices continued to rise in the fourth quarter of 2025. National median prices rose 1.2% year over year to $414,900.”

That’s not the rapid growth of a few years ago, but it’s not a downturn either. And just to really drive this home, here’s a look at the data from NAR at a regional level, so you can see that the negative narrative spun up online isn’t the whole truth (see graph below):

a graph of a number of housesHome prices are up (or at least holding steady) in the Northeast, Midwest, and South. The West has seen some small declines in certain markets, but “small” is the key word.

There is no wave of falling prices across the country. Instead, there are just a few pockets adjusting after several years of what’s typically considered unsustainable or exponential growth.

Yes, Some Markets Have Come Down, But Look at the Bigger Picture.

Okay, but what about the places where prices have declined? According to ResiClub and Zillow, that’s not a cause for major concern. When you zoom out and look at those same markets over the past five years, the story changes (see graph below):

a graph of a number of percentIn the areas with recent declines, home values are still significantly higher than they were just five years ago. That’s a direct reflection of how much home values have gone up.

Online chatter tends to shine a spotlight on the few areas that are down. But the bigger picture shows most homeowners are still in a very strong position.

Of course, every market, and every home, is different. But broadly speaking, home values are holding steady. And this isn’t a sign of widespread trouble in the market.

Bottom Line

Despite what you may be seeing online, home prices are rising or holding steady in most parts of the country.

If you’re curious what your home is worth today, let’s take a look at the numbers together. Because context, and local expertise, matter more than what you’re seeing online.

For Buyers • For Sellers • Home Prices • February 25, 2026

How Your Equity Could Help Younger Generations Buy a Home

For a lot of parents or grandparents, watching a family member struggle to buy their first home right now is hard. That’s because you saw firsthand how homeownership gave your life more stability and helped grow your net worth – and you want your loved ones to have those same opportunities.

But with all the affordability challenges in recent years, that can feel like an uphill battle – even though it’s slowly improving lately. Here’s what you may not realize. You may be in a unique position to help (thanks to the equity in your current house).

The Equity Advantage You May Not Be Thinking About

You’ve likely owned your home for years, maybe even decades. And during that time, two things happened:

  • Home values rose
  • Your mortgage balance shrank (or you paid it off entirely)

That combination has created substantial equity for many homeowners like you.

And while you may think of that equity as something you want to have in your pocket for retirement, it can also serve another purpose: helping the next generation clear the biggest hurdle in their way.

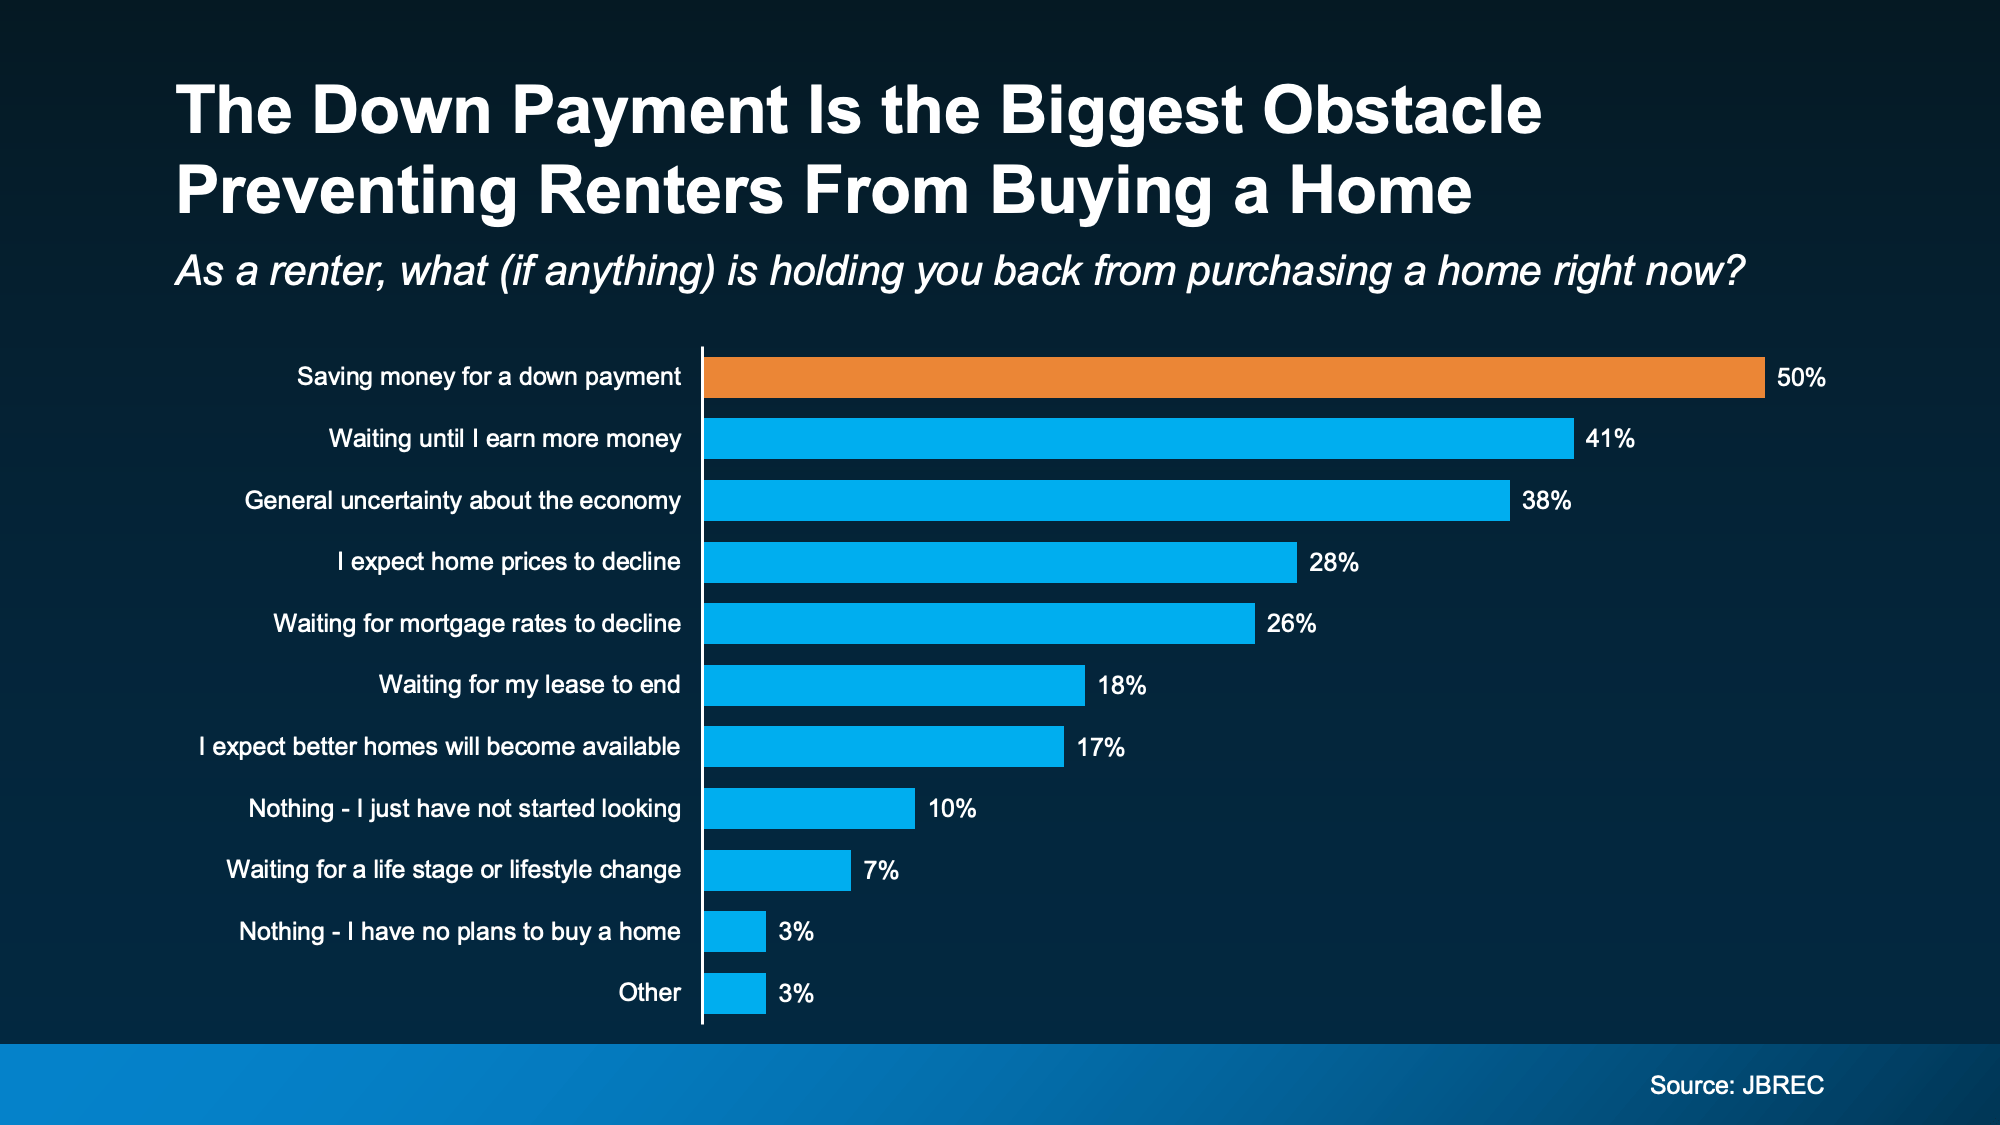
The #1 Thing Holding Young Buyers Back

When John Burns Research & Consulting (JBREC) asked renters what’s keeping them from buying, the top answer wasn’t mortgage rates or home prices. It was the upfront cost, particularly saving enough for their down payment (see graph below):

a graph of a home purchaseThat’s where you may be able to make more of a difference than you realize. You can’t control rates or prices. But you may be able to use your equity to help with this upfront expense. And giving money to your loved one so they buy a home doesn’t mean putting your own future at risk.

Even a small portion of your equity can put them in a position to finally get the keys to their first place – and, if you’re strategic about it, you’d still have a lot leftover for when you retire.

With an estimated $68 and $84 trillion of wealth expected to transfer from older generations to younger ones over the next two decades, many families are already thinking differently about when and how that wealth will be passed down. Maybe it makes sense for your family to think about too.

Help from Loved Ones Is Making a Move Possible for Many First-Time Buyers

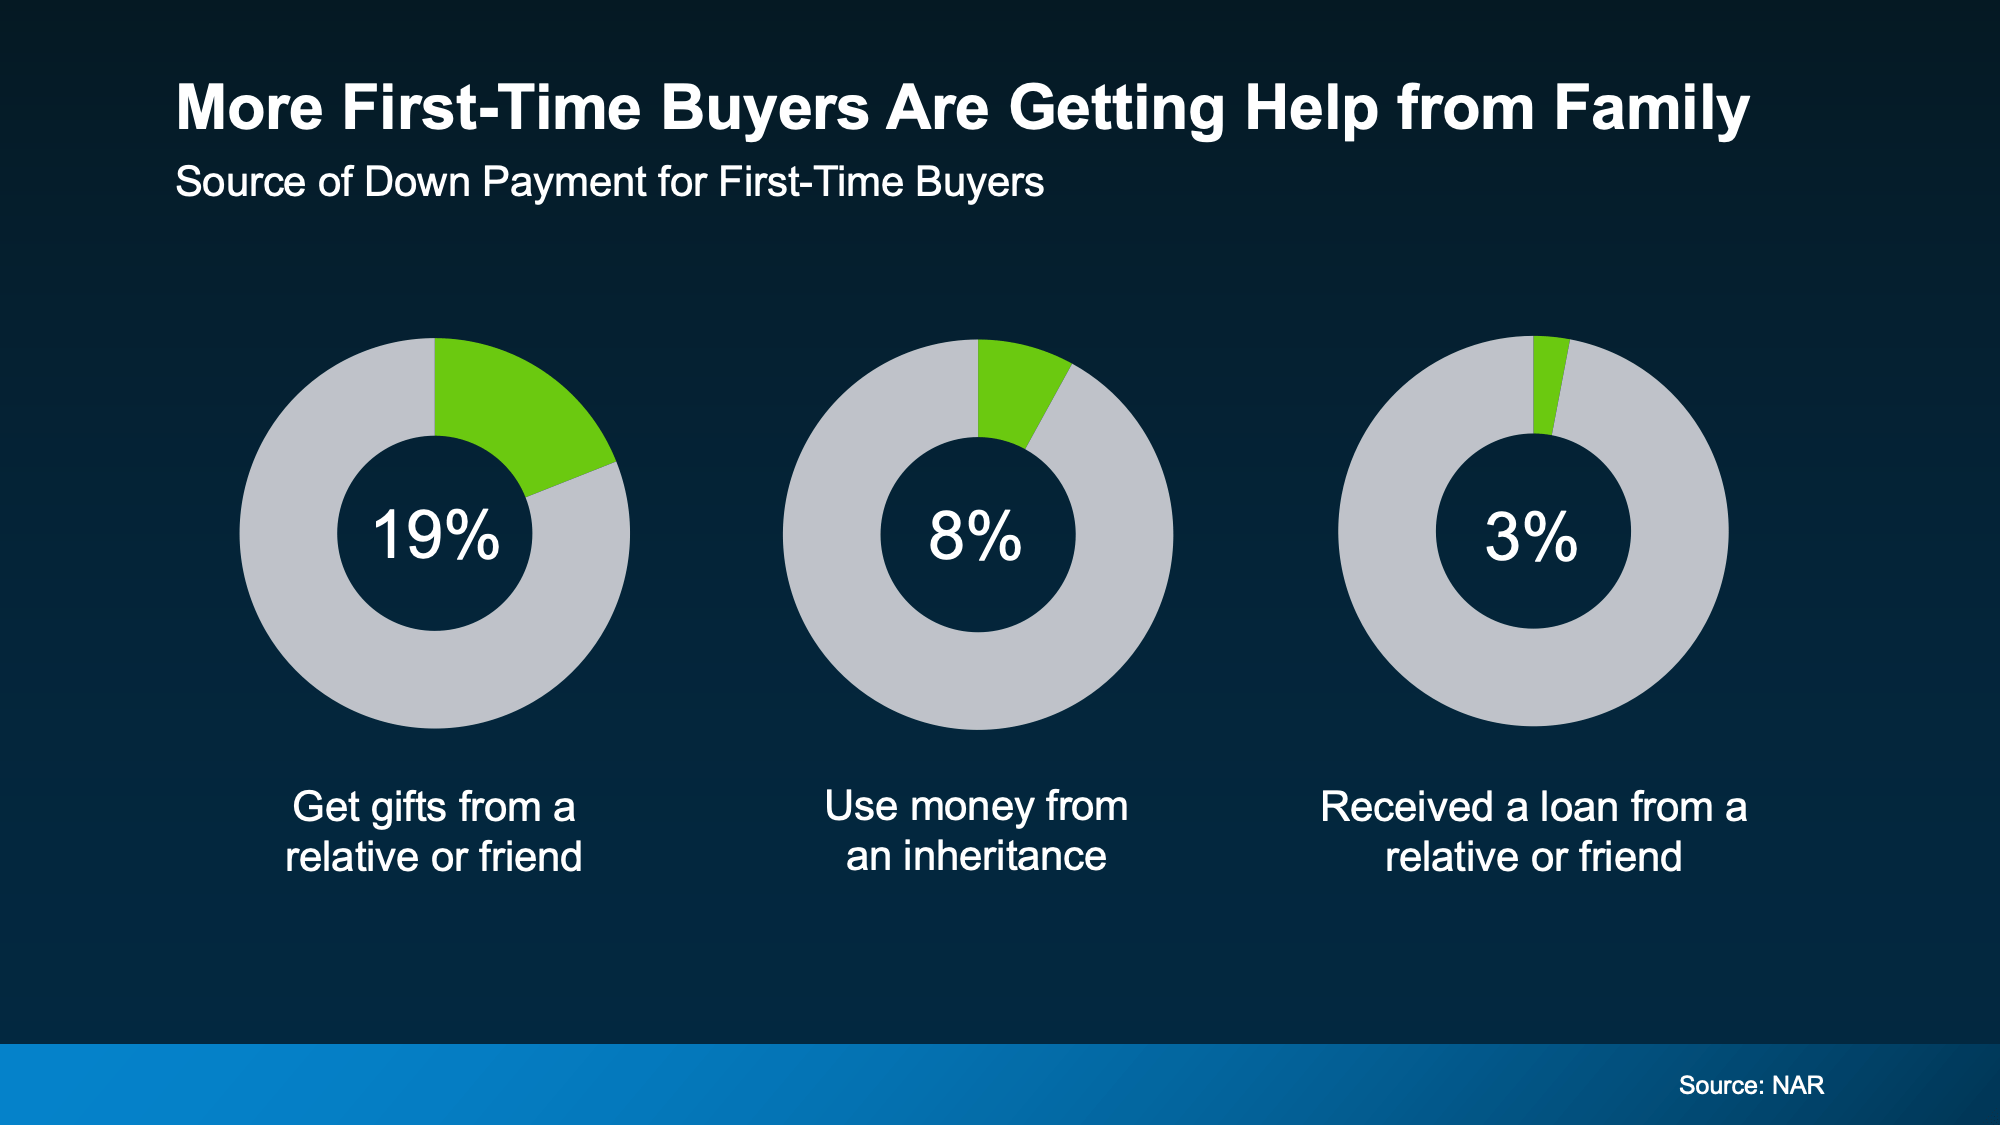
A growing share of young buyers are using gifts and loans from their loved ones to springboard into homeownership. According to the National Association of Realtors (NAR), nearly 1 in 5 first-time buyers use a cash gift from their family or loved ones for their down payment.

And other young buyers are using their inheritance or a loan from someone they know to finally break into the market (see charts below):

This Is About Opportunity, Not Obligation

Every family’s situation is different, and your decision should be made carefully. It’s just that, if you’ve built up a lot of equity, you may have more room to help than you think.

It’s not just a financial gift. It’s giving stability, security, and a foundation that could change their lives for the better – especially at a time when they may not be able to do it on their own.

Bottom Line

If you’re curious what your home equity could make possible, for you or for your loved ones, let’s start with a simple conversation. Because sometimes the most meaningful investment you can make is for the next generation.